
A company doesn't become public merely because it is famous, profitable or has hundreds of employees. And a company isn't small simply because its name ends in “Private Limited”. Those words describe its legal ownership and fundraising framework—not the size of the business.
Imagine two businesses: a private manufacturing company with ₹100 crore in annual sales and three shareholders, and an unlisted public company with ₹2 crore in sales and eight shareholders. Both structures are legally possible. The distinction comes from their Articles of Association, membership rules, share-transfer arrangements and ability to invite the public to invest.
This guide explains the difference under the Companies Act, 2013, including the December 2025 small-company update, how compliance changes, and what a business must consider before converting from one form to the other.
Public company ≠ listed company. Listing securities on a recognised stock exchange is a separate regulatory step. Similarly, private company ≠ small company: “small company” has a separate definition and financial criteria under Section 2(85).
Private company vs public company: differences at a glance
| Point | Private limited company | Public limited company |
|---|---|---|
Main legal definition | Section 2(68) | Section 2(71) |
Normal name suffix | Private Limited | Limited |
Minimum members on incorporation | 2; an OPC has 1 | 7 |
Maximum members | Generally 200, with statutory counting exclusions | No general statutory maximum |
Minimum directors | 2 (OPC: 1) | 3 |
Share transfers | Restricted by the Articles of Association | Generally freely transferable under Section 58, subject to law and valid arrangements |
Invitation to the public to subscribe | Prohibited | Possible, subject to securities and public-offer requirements |
Stock-exchange listing | Not as a private company | Optional; a public company may remain unlisted |
Small-company classification | Possible when Section 2(85) conditions are satisfied | Excluded |
Corporate-governance obligations | Baseline company-law rules with applicable exemptions | Additional rules may apply, especially if listed or above prescribed thresholds |
Conversion | Can convert to public | Can convert to private with prescribed government approval |
The minimum membership and director counts are statutory rules. They aren't a measure of how much money the company can earn. Refer to the Companies Act, 2013 on India Code for Sections 2, 3, 14, 23, 58 and 149.
What makes a company private under Section 2(68)?
A private company must include particular restrictions in its Articles of Association (AOA). Its Articles restrict the right to transfer shares, generally limit membership to 200 and prohibit inviting the public to subscribe for its securities. The 200-member limit has statutory counting exceptions—for instance, qualifying employee-members—and jointly held shares are counted under the prescribed rule.
That structure works for businesses whose ownership remains with founders, family members, a promoter group or selected investors.
What happens when a shareholder wants to sell?
Suppose three people hold shares in an engineering firm: A owns 50%, B owns 30%, and C owns 20%. B wishes to sell their holding to an outside investor.
The sale must follow the company's Articles. Depending on the actual AOA, that may involve first offering the shares to existing members or following a specified approval process. Not every private company uses the same transfer restriction, so shareholders should read its AOA and any valid shareholders' agreement before signing a sale contract.
Can a private company raise money from outside investors?
Yes. A private limited company can use legally permitted methods such as rights issues and private placements. It may attract angel investors, venture capital or other strategic investors without first turning into a public company. The relevant issue, allotment, valuation and filing rules still apply.
What it cannot do is make a general public invitation for subscription in breach of its private-company restrictions.
What makes a company public under Section 2(71)?
A public company is generally a company that is not a private company. The Act also contains a special rule deeming a subsidiary of a public company to be a public company for purposes of the Act even where its Articles remain those of a private company. That exception is worth checking in group-company structures.
A conventional public company must have at least seven members and at least three directors. It can accommodate a broader shareholder base, and lawful public fundraising may be available subject to Companies Act and SEBI requirements.
Listed public company vs unlisted public company
A listed public company has securities listed on a recognised stock exchange and faces the securities-law and exchange obligations that apply to it.
An unlisted public company is registered as a public company but does not have securities listed on a recognised exchange. It does not automatically have an IPO, daily share trading, or a quoted market price. Its shares may be legally transferable but difficult to sell when there is no ready buyer.
Before investing or joining a company's board, check its class, listing status and filings using MCA's company master-data services Official ↗. Do not infer listing status from the word “Limited” alone.
Why share-transfer rules matter to founders and investors
A shareholding arrangement affects control, fundraising and exits. Founders of a private company may prioritise knowing who can become a shareholder, while an investor might want a clearer path to selling a stake later.
Section 58 recognises the free transferability of securities in a public company, but applicable law and lawful contracts still matter. Freely transferable does not mean instantly saleable: an unlisted public company's shares may be illiquid.
For either structure, a serious investor should examine the AOA, shareholding records, restrictions and approvals—not simply the name on the certificate of incorporation.
Does “private” mean a small company? The 2025 rule change
No. A small company is a separate statutory classification under Section 2(85). Following the Companies (Specification of Definition Details) Amendment Rules, 2025, notified on 1 December 2025 , the prescribed financial limits are:
Small company limits (effective 1 December 2025)
Paid-up share capital
Up to ₹10 crore
Both financial limits must be satisfied
Turnover
Up to ₹100 crore
Check turnover for the relevant preceding financial year
The company must meet both criteria and must not fall into an excluded category. Public companies, holding companies, subsidiary companies, Section 8 companies and companies governed by a special Act are excluded as specified in Section 2(85).
Consider a hypothetical closely held private company with paid-up capital of ₹4 crore and turnover of ₹75 crore. It may meet the financial thresholds, but its classification still requires checking the statutory exclusions. Another private company with turnover of ₹150 crore can remain private; it simply does not satisfy the turnover limb of the small-company definition.
Some older articles still cite ₹4 crore and ₹40 crore as the small-company thresholds. Those figures predate the December 2025 amendment. Small-company classification also differs from MSME/Udyam classification, which is governed by separate rules.
How company names work: Pvt Ltd, Ltd, OPC and Section 8
“ABC Engineering Private Limited” usually denotes a private company. “ABC Engineering Limited” usually denotes a public company. An OPC is a specially regulated private company with one member and ordinarily uses “(OPC) Private Limited” in its name.
A Section 8 company formed for charitable or similar statutory objects has distinct rules and may be licensed to omit “Limited” or “Private Limited” from its name. This is another reason to verify a company's legal form through MCA records instead of guessing from its trading name.
For an explanation of company identification details, see TaxQue's CIN number guide.
How governance and annual compliance differ
Both forms are companies under the Act. They generally need proper books of account, annual financial statements, statutory registers, board and shareholder processes, an auditor and applicable ROC filings. A public company does not replace these requirements; in various circumstances it has more obligations.
Private company compliance
Private companies may benefit from specified exemptions and relaxations, depending on the company's status and whether exemption conditions are met. Qualifying small companies can receive particular procedural simplifications, but they are not exempt from maintaining accounts, statutory audit or required annual filings merely because they are small.
See TaxQue's annual compliance guide for private companies.
Public company compliance
Additional governance rules may apply based on whether the public company is listed, its paid-up capital, turnover, borrowings or other prescribed criteria. Examples include independent directors, audit and nomination/remuneration committees, key managerial personnel, secretarial audit and additional disclosures.
Don't assume these requirements apply identically to all unlisted public companies. A company should determine each provision's applicability separately. Listed entities must also evaluate the relevant SEBI rules, including applicable disclosure and governance requirements.
A practical cost question
If two founders can raise their planned investment privately, the public-company structure may add governance work without solving a current funding problem. But if a business has a genuine plan to invite public subscriptions, conversion may become part of its financing roadmap. The choice is commercial as well as legal.
Which structure should you choose for your business?
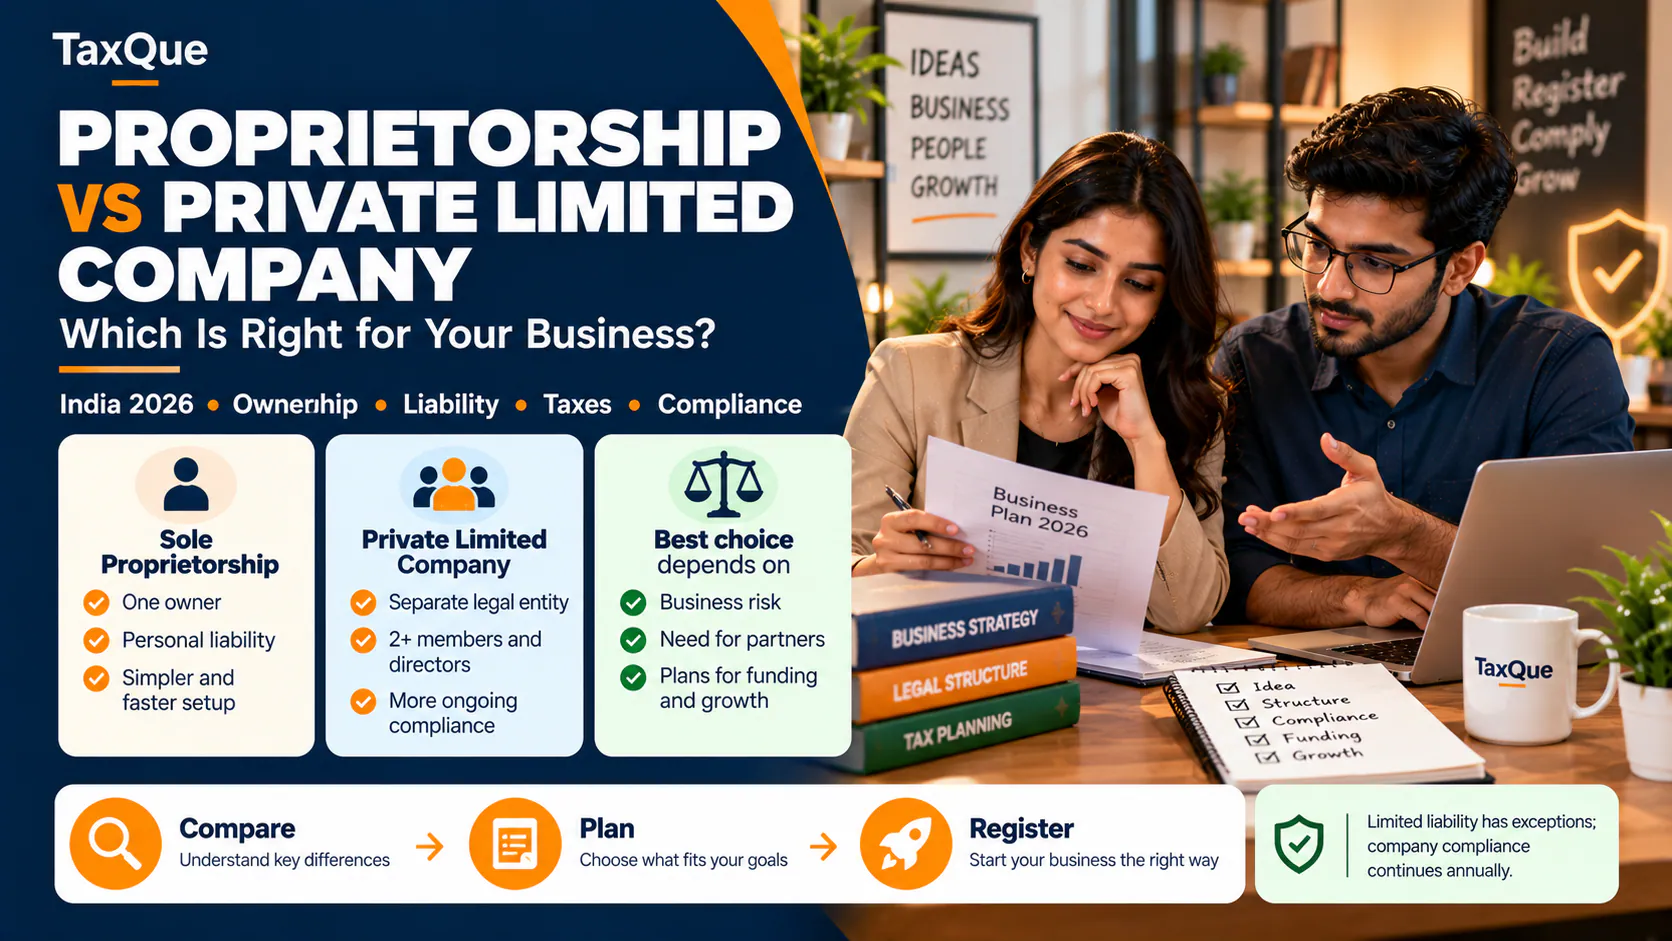
For a start-up, family enterprise, consultancy or manufacturing business with a limited group of owners, a private limited company is often an appropriate starting point. It can accommodate investors through lawful private funding routes while preserving defined ownership controls.
A public company becomes more relevant when a business requires a wider shareholder base, is exploring lawful public securities offers or is preparing for a potential listing. It should be evaluated alongside the cost of governance and securities compliance.
Practical choice guide
Private limited company
- Prefer a closely held shareholder group
- Need selected angel/VC or strategic investment
- Want share-transfer rules in the AOA
- No present need for public subscription
Public limited company
- Need broader shareholder participation
- Plan to explore public fundraising
- Considering future stock-exchange listing
- Prepared for applicable public-company governance
These are planning considerations, not automatic eligibility tests. A lawyer or company secretary should review a particular fundraising strategy before offers are made.
Converting a private limited company into a public limited company
Section 14 permits the Articles to be altered for conversion. It is not the same as going public through an IPO.
Private to public: practical sequence
-
Review eligibility
Check the AOA, shareholding, directors, agreements, filing status and proposed ownership structure.
-
Meet minimum counts
Arrange at least seven members and three directors if the company does not already have them.
-
Board approval
Convene the board to approve the proposal, draft AOA changes and call a general meeting.
-
Special resolution
Obtain the shareholders' special resolution to alter the Articles and approve consequential changes.
-
ROC filings
File the resolution in MGT-14 as applicable and the conversion application in INC-27 with the required attachments and fees.
-
Update records
Follow ROC processing and obtain updated incorporation records, then update statutory registers and relevant business records.
The filing's exact attachments, statutory timelines and portal validation requirements should be checked against the current MCA INC-27 instruction kit Official ↗ before submission. Existing contracts or financing arrangements may need consent even though a routine private-to-public conversion does not generally require the Regional Director approval used for the reverse route.
Converting a public limited company into a private limited company
This direction is more involved. The company must change its Articles and obtain the approval prescribed under Section 14, currently administered through the Regional Director process.
Public to private: practical sequence
-
Check eligibility
Review shareholder numbers, AOA, listed status if relevant, creditors, outstanding defaults and restrictions.
-
Board and members
Obtain board approval and pass the required special resolution at a general meeting.
-
File the resolution
Complete MGT-14 filing and prepare the required documents, declarations and notices.
-
Apply for approval
Submit RD-1 with supporting material under the applicable Companies (Incorporation) Rules, including Rule 41.
-
Address objections
Meet any advertisement, creditor, stakeholder and regulatory notice requirements, and respond to RD queries.
-
Complete ROC conversion
After the RD's order, complete the prescribed INC-27 process and obtain updated company records.
Rule 41 generally requires the RD-1 application within 60 days of the special resolution. The precise notice and filing conditions must be checked for the facts of the company. Companies with listed securities need a separate securities-law assessment; an ordinary RD application cannot be treated as a substitute for any required delisting process.
The MCA INC-27 instructions Official ↗ distinguish the public-to-private route by requiring information linked to the RD-1 approval.
Documents and checks before incorporation or conversion
- ○ Draft or existing Memorandum and Articles of Association.
- ○ Proposed member/shareholding details and director appointments.
- ○ Identity, address and registered-office documents applicable to the transaction.
- ○ Board and shareholder resolutions, notices and meeting records.
- ○ Latest statutory filings and any pending ROC compliance issues.
- ○ Existing financing agreements and shareholder transfer provisions.
- ○ Applicable consents, declarations, RD approval and supporting documents, where required.
- ○ Updated MCA filing instruction kits and applicable professional advice.
For initial incorporation paperwork, see documents required for company registration.
Mistakes worth avoiding
“Public means listed.” An unlisted public company is a lawful company category. Listing is a separate process.
“Private means small.” A private company can have substantial revenue. The small-company definition applies only if financial and other criteria are met.
“Private firms can't take investor money.” They can use legally permitted private fundraising methods.
“All public companies must have the same committees.” Several governance duties depend on listing and prescribed thresholds.
“Conversion is just changing Pvt Ltd to Ltd.” It involves shareholder approvals, changes to the Articles, regulatory filings and—in public-to-private conversion—prescribed government approval.
“Once converted, all tax registrations automatically update.” The company must examine changes required in its MCA, banking, contractual and other regulatory records; do not assume downstream systems will update themselves.
Final takeaway: choose the ownership model, not the label
The private-versus-public decision should start with three questions: Who should be able to own shares? How will investors enter and exit? Do you need a public-offer route? Company turnover alone does not answer any of them.
If your founders want a controlled shareholding structure and private investment, private limited may be the right fit. If a wider shareholder base or public fundraising is central to your plans, public limited deserves serious assessment. Either way, the Articles, compliance position and capital strategy need to agree with the chosen structure.
TaxQue can help you review incorporation requirements, documents and the filing steps relevant to your business. Explore private limited company registration, public limited company registration or our broader company services.
Explore company registration services
Official sources and verification references
- Companies Act, 2013 — India Code : Sections 2(68), 2(71), 2(85), 3, 14, 23, 58 and 149.
- Government of India e-Gazette — Notification G.S.R. 880(E), 1 December 2025 : revised financial ceilings for small companies.
- MCA — INC-27 webform instruction kit Official ↗: public/private conversion-related filings and fields.
- MCA portal Official ↗: official company master data, e-forms and current filing services.
Legal-information note: This guide describes the general position as reviewed on 16 October 2026. Actual conversion eligibility, approvals, MCA fees and return/filing requirements must be confirmed for the specific company and current portal rules before proceeding.