
If you start a business alone, a sole proprietorship may be enough. But what happens when a customer offers you a large contract, you take a business loan, or someone wants to invest in your idea?
The choice between a sole proprietorship and a private limited company is not only about registration fees. It changes who legally owns the business, who carries the debt, how money can be raised and what must be filed every year.
Imagine two people with similar small businesses. Asha runs a consultancy on her own and invoices a few clients each month. Rohan plans to manufacture electrical equipment with a co-founder, hire staff and take a large equipment loan. The simplest structure for Asha may not be the safest or most practical structure for Rohan.
Here is how to decide—with clear comparisons, examples and the legal steps if you later move from a proprietorship to a company.
2026 tax-law context: The Income-tax Act, 2025 applies from 1 April 2026 for Tax Year 2026–27 onward. Earlier years remain governed by the Income-tax Act, 1961. Where the rules differ, check the relevant tax year instead of applying an old section number automatically. Income Tax Department Official ↗.
Proprietorship vs private limited company: the short answer
A sole proprietorship can work well when one individual runs a small, relatively low-risk business and wants straightforward ownership and administration. The individual and the business are not separate legal persons.
A private limited company generally makes more sense when there are co-founders, outside shareholders, material contractual exposure, or plans to build an investor-backed enterprise. The company is a separate legal person, but it costs more to establish and administer.
Neither is automatically better. Your risk, profit level, financing plan and time available for compliance matter more than the size of your website or the word “Limited” in your name.
Which structure fits your plan?
Proprietorship
- One individual owns and controls the business
- Business debts can reach the proprietor personally
- Usually simpler administration and lower fixed compliance cost
- Cannot issue company equity shares
Private limited company
- Separate legal entity with shareholders and directors
- Shareholder exposure is generally limited, subject to exceptions
- Incorporation and recurring company-law filings
- Can issue shares through legally permitted processes
Side-by-side comparison: 14 important differences
| Question | Sole proprietorship | Private limited company |
|---|---|---|
Separate legal person? | No; legally linked to the proprietor | Yes, once incorporated |
Typical ownership | One individual | Usually 2–200 members, with statutory counting exclusions; OPC is different |
Minimum directors | Not applicable | Two for an ordinary private company |
Personal liability | Generally unlimited | Generally limited to unpaid share capital, subject to guarantees, fraud and other legal exceptions |
Registration route | Activity-based registrations as applicable; no single national incorporation certificate | MCA incorporation under the Companies Act, 2013 |
Main identity numbers | Owner's PAN; GSTIN/Udyam and licences where applicable | Company CIN, PAN and TAN; GSTIN as applicable |
Decision-making | Proprietor takes decisions | Board, shareholders, AOA and statutory process matter |
Raising equity | Cannot issue shares | Can allot shares under applicable law |
Borrowing | Credit depends on proprietor and business | Company can borrow; founders may still give guarantees |
Income tax | Owner taxed as an individual | Company taxed separately; personal receipts from company may have their own tax treatment |
Audit | Tax audit only if applicable; other laws may require audits | Statutory financial-statement audit generally required |
Annual ROC filings | Not applicable as a company | Required under company law |
Continuity | Dependent on proprietor; succession requires planning | Separate existence continues despite changes in shareholders |
Closure | May be simpler, but liabilities and cancellations remain | Formal company closure/strike-off or winding-up rules apply |
Important: An OPC (One Person Company) is a form of private company with its own provisions, not the same thing as an unincorporated sole proprietorship. Companies Act, 2013 Official ↗.
1. Legal identity and liability: what happens if the business owes money?
In a proprietorship, personal and business risks are connected
Suppose a proprietor owes a supplier ₹8 lakh. The trading name has no independent corporate existence that automatically shields the owner's property. Subject to the applicable recovery process, the creditor can pursue the proprietor personally.
The same general exposure can matter with unpaid business loans, contractual claims and litigation. A separate current account or GST registration does not by itself create limited liability.
In a company, there is a separate legal person—but not total immunity
A private limited company can own equipment, enter contracts, sue and be sued in its own name. Shareholders' liability is ordinarily limited by the share structure. Nevertheless, a director or shareholder may still face personal exposure when they:
- Sign a personal guarantee for company borrowing.
- Engage in fraud, wrongful conduct or personally actionable acts.
- Incur liabilities under legislation that specifically fixes responsibility on individuals.
- Fail to comply with particular statutory obligations.
Example: If a company borrows ₹30 lakh and the founder signs a personal guarantee, incorporation alone will not cancel that guarantee if the company defaults.
Choose a company to create an appropriate legal structure, not on the assumption that its directors can never be personally responsible.
2. Owners, control and admitting investors
A proprietorship has one proprietor. A family member may help manage it, and employees may be hired, but a second person cannot simply receive “30% shares” in the proprietorship as if it were a company.
An ordinary private company is formed with at least two subscribers and generally needs at least two directors. Shareholders may appoint directors and the Articles of Association may restrict share transfers. Section 2(68), Section 3 and Section 149 of the Companies Act provide the basic framework.
If an investor offers ₹25 lakh in return for 20% equity, a private company can consider an appropriate share allotment, valuation and shareholder arrangement. A proprietorship would need a different structure or restructuring before this kind of equity participation.
A lender's willingness to finance a business depends on financials, cash flow, security and credit history—not just “Private Limited” in the name. Becoming a company does not guarantee an unsecured loan.
3. Tax comparison in 2026: which structure actually pays less?
The original temptation is to compare a proprietor's highest individual slab with a company's concessional corporate rate. That comparison misses the point: you must compare the total tax on business profits and the money eventually reaching the owner.
Proprietorship: individual tax treatment
The proprietor reports eligible business or professional profit in the individual return and uses the applicable income-tax regime. Under the new regime, qualifying resident individuals with taxable income up to ₹12 lakh may receive a rebate on normal slab-rate income, subject to the law's conditions. The rebate is not a universal exemption for every kind of income. Under the 2025 Act, see Section 156 Official ↗.
Some eligible taxpayers can also use presumptive taxation, subject to their business, turnover, receipt pattern and statutory conditions. That possibility must be checked separately; it is not a benefit automatically available to every proprietor.
Private company: company-level tax, then possible shareholder tax
For qualifying companies opting into the concessional corporate regime, a 22% base rate plus 10% surcharge and 4% cess produces an illustrative effective rate of 25.168%. Eligibility, the exercise of an option and restrictions on specified deductions matter. This is not every company's automatic rate. Income Tax Department—concessional company regime Official ↗.
If a company distributes profits as dividends, the shareholder may face tax on those dividends as applicable. Genuine remuneration to a working director involves different accounting and tax treatment; it is not equivalent to freely withdrawing a proprietor's own cash.
Worked example: ₹10 lakh annual taxable business profit
Assume both businesses have ₹10 lakh of taxable profit, no other income, and no unusual deductions or special-rate income. Assume the proprietor is a resident individual eligible for the normal-income rebate, and the company validly uses the concessional regime.
| Illustration | Proprietorship | Private company |
|---|---|---|
Taxable business profit | ₹10,00,000 | ₹10,00,000 |
Income-tax calculation | Eligible individual rebate may reduce normal-rate tax to nil | 22% + 10% surcharge on tax + 4% cess |
Illustrative business-level tax | ₹0 | ₹2,51,680 |
After-tax profit remaining in the business | ₹10,00,000 | ₹7,48,320 |
These figures do not compare dividend taxation, director remuneration, other incomes or the commercial benefits of limited liability. They simply show why “a company always saves tax” is inaccurate. The preferred structure at ₹30 lakh or ₹1 crore profit still depends on how profits will be used and the tax options actually available.
Tax-year caution: The ₹12 lakh threshold is the normal-income rebate for eligible resident individuals, not a promise of tax-free treatment for capital gains or other special-rate income. Official tax rate and rebate guidance Official ↗.
4. How much does each structure cost to start and maintain?
There is no reliable one-price answer for India. The initial cost of a private company changes with the state of the registered office, capital structure, digital signature needs, stamp duty and professional services. Local licensing costs also vary for proprietors.
| Cost area | Proprietorship | Private limited company |
|---|---|---|
Government incorporation | No MCA incorporation needed | MCA filings and applicable stamp duty |
Digital signatures | Depends on filings needed | Generally required for relevant MCA filings |
Udyam registration | Government portal is free | Government portal is free if eligible |
GST registration | Government registration application ordinarily free; professional help optional | Same GST registration principle |
Accounting | Based on volume and applicable tax law | Books, financial statements and stronger internal recordkeeping |
Audit | Tax audit or other audit where triggered | Statutory audit generally required |
ROC annual filing | Not a proprietorship obligation | Financial statements, annual return and other relevant filings |
Closing costs | Cancellation, dues and contracts | Formal company closure and outstanding compliance |
Do not confuse free government registration with a free commercial service. Udyam registration is free on the official MSME portal .
Why a company can cost money even when it has no turnover
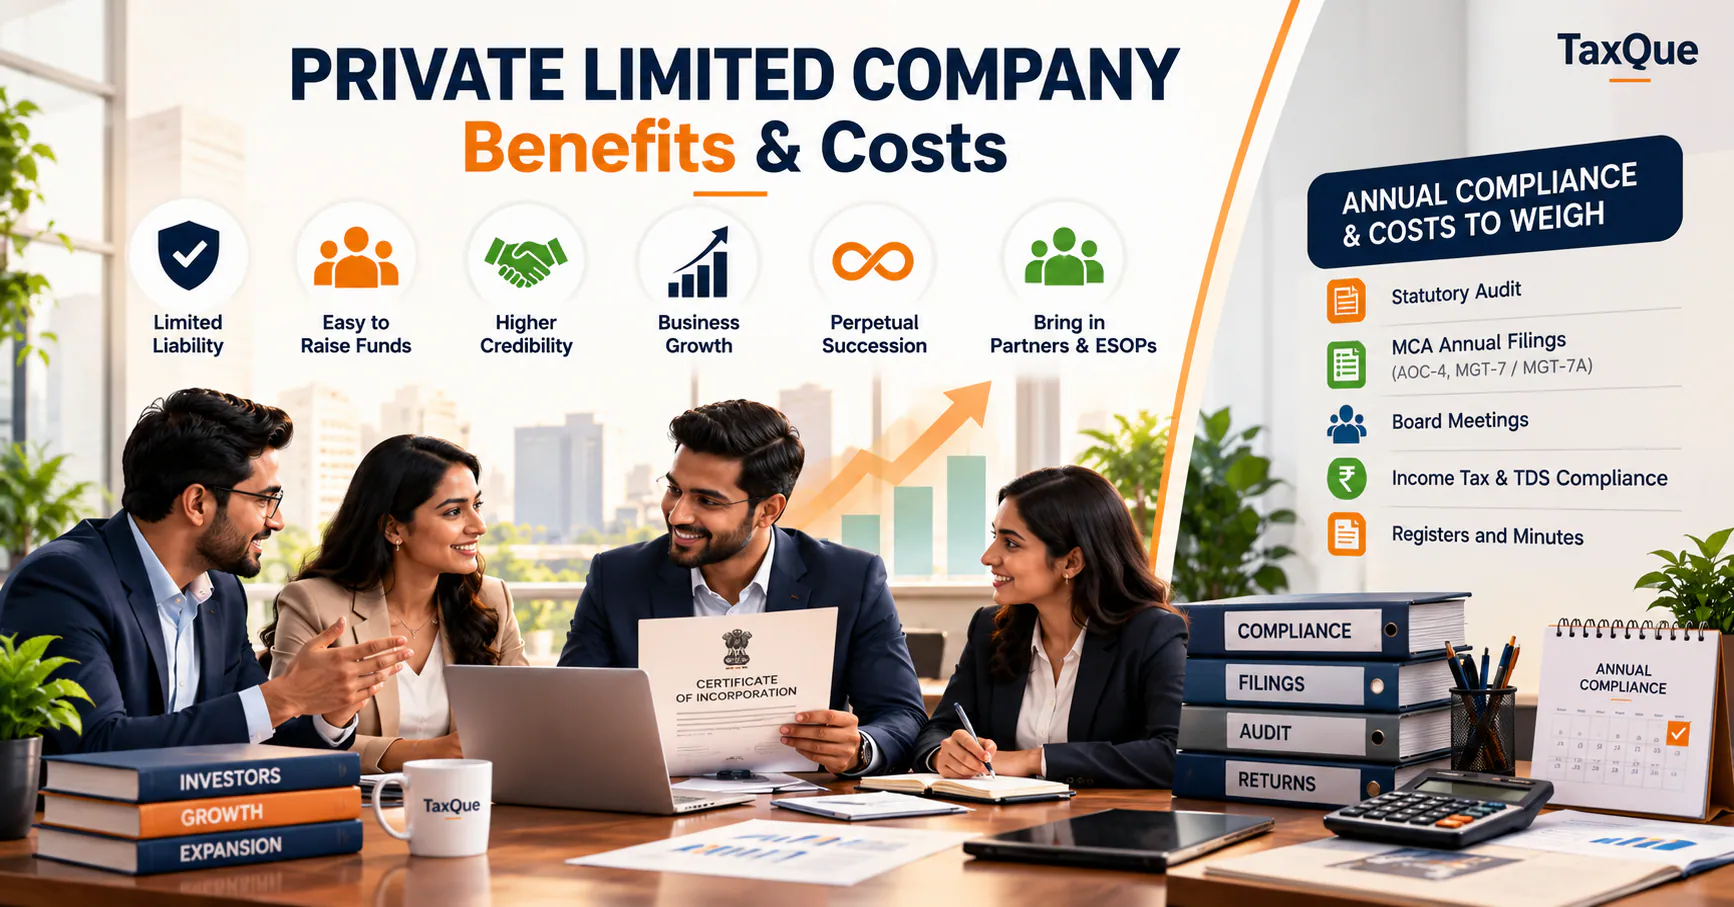
Many new founders assume they can ignore filings until sales begin. A company generally must maintain books, appoint auditors as required, prepare financial statements and comply with applicable MCA annual-filing and governance obligations—even in a year with little or no business activity. Exact forms and exemptions depend on its legal status.
By contrast, a proprietor generally does not file a company annual return, although income-tax, GST, labour and local-law obligations can still exist.
5. Company registration versus proprietorship registration
Starting a sole proprietorship
No single national certificate creates a sole proprietorship under the Companies Act. Instead, the proprietor establishes the activity and obtains registrations the business actually needs.
Practical start-up checklist for a proprietor
-
Business plan
Confirm the trade, services, location and customer types.
-
Tax and bank identity
Use the proprietor's PAN and arrange suitable banking documentation.
-
Udyam
Apply on the official portal if eligible; registration is free.
-
GST
Determine whether GST registration is mandatory or commercially useful under the applicable rules.
-
Local licences
Check shop and establishment, trade, FSSAI and any sector-specific requirements.
-
Records
Keep invoices, expenses, bank reconciliation and tax records from day one.
Government Udyam portal | GST portal Official ↗
Registering a private limited company
MCA incorporation overview
-
Decide ownership
Finalise at least two subscribers, directors, shareholding and proposed business objects for an ordinary private company.
-
Verify identity
Arrange DIN/DSC requirements and director or subscriber documents.
-
Reserve name
Apply using SPICe+ Part A where applicable.
-
Submit incorporation
Complete SPICe+ Part B, e-MOA, e-AOA and linked filings as applicable.
-
Obtain credentials
On approval, retain the Certificate of Incorporation, CIN, PAN and TAN.
-
Complete first-year steps
Open and operate the company bank account; assess INC-20A, auditor appointment, registers, share certificates and other due dates.
MCA's SPICe+ guidance Official ↗ explains linked incorporation services, including PAN/TAN and optional GST registration. Actual upload fields and attachments must be checked on the live MCA portal.
6. Funding, contracts and credibility: what genuinely changes?
A proprietor can hire employees, sign substantial contracts, open business accounts and obtain loans. There is no general law that limits proprietorships to tiny businesses. Some institutions may, however, require a particular constitution or additional assurances.
A company provides a distinct ownership framework that can be useful for co-founders, institutional investors, ESOP planning and certain larger supply contracts. But whether a customer, bank or tender authority prefers a company depends on its own documented criteria.
Hypothetical example: A freelance designer charging ₹8 lakh per year may find a proprietorship sufficiently practical. A product startup with two founders, several employees and a planned angel round may prefer a company well before it has significant revenue.
Neither example is a mandatory rule; it is a way to match legal structure to operating needs.
7. Can you convert a sole proprietorship into a private limited company?
Yes, but the practical process normally involves incorporating a company and transferring the proprietorship's business to it. A proprietor does not simply change the trading name and keep all registrations untouched.
The seven-step transfer checklist
- Review the business: prepare financial statements, debtors, creditors, stock, fixed assets, employee records, contracts and outstanding tax liabilities.
- Choose the shareholders and directors: plan the company's capital and who owns shares after succession.
- Incorporate the company: obtain its CIN, PAN, TAN and other essential registrations.
- Document the business transfer: determine the agreement, effective date, business assets and liabilities, consideration and any lender or customer consent.
- Review income tax: test whether the succession meets the statutory non-transfer conditions and avoid making taxable assumptions before the documents are signed.
- Handle GST and other registrations: evaluate new GST registration, cancellation/amendment steps, input-tax-credit transfer if eligible and relevant licence updates.
- Switch operations carefully: update invoices, bank mandates, purchase orders, payroll, vendor details, insurance and website legal disclosures.
The capital-gains relief condition many guides omit
Under Section 70(1)(zf) of the Income-tax Act, 2025, a qualifying succession can be excluded from capital-gains transfer treatment when all relevant assets and liabilities move to the company, the previous proprietor retains at least 50% voting power for five years, and receives consideration only in company shares. These are cumulative conditions, not optional suggestions. The prior-law counterpart was Section 47(xiv). Income Tax Department: Section 70 Official ↗.
Failing a condition or having a different transaction structure may change tax treatment. Obtain transaction-specific tax advice before transferring appreciated assets, goodwill or property.
What happens to GST input tax credit?
GST law provides a route for transfer of unutilised input tax credit upon a qualifying business transfer with transfer-of-liabilities conditions, using Form GST ITC-02 where applicable. The credit does not simply move to the company's electronic credit ledger because the proprietor has issued a transfer invoice. GSTN forms guidance Official ↗.
A new company has a different PAN. Do not continue issuing its invoices under the proprietor's old GST registration without checking the transfer date, registration position and applicable GST requirements.
8. Three realistic business scenarios
Scenario A: a solo service professional
Asha makes a modest profit, works alone and has no external investor. She values a low fixed administrative cost and can manage professional liability through sound contracts and appropriate insurance. A proprietorship may be a practical starting choice.
Scenario B: a manufacturing and trading venture
Rohan and his co-founder plan to purchase machinery, sign distributor agreements and borrow against business assets. A private company may provide a better ownership and governance structure, though the bank may still request director guarantees.
Scenario C: an established proprietor preparing for outside investment
Meera runs a profitable distribution business, employs staff and wants to issue 15% equity to an investor. She should model a documented business succession, company incorporation and applicable tax/GST transition before promising the investor that shares can be issued.
9. Mistakes that cost founders money
- Believing a GSTIN creates a company. GST registration is a tax registration, not incorporation.
- Assuming private limited means no personal liability. Guarantees and legal exceptions still matter.
- Choosing only by the quoted income-tax rate. Compare full company tax, director pay, dividends and compliance costs.
- Assuming Udyam registration has an official fee. Government Udyam registration is free.
- Issuing “shares” in a proprietorship. Equity allotment needs an appropriate legal vehicle.
- Forgetting annual MCA compliance in low-revenue years. Company filing duties do not vanish with low sales.
- Transferring a business without checking contracts and taxes. Business succession can involve stamp duty, lenders, GST and income-tax conditions.
- Treating bank credit as guaranteed. Company status alone does not substitute for cash flow, collateral or financial history.
10. Quick decision checklist before you register
- ○ Will anyone own equity other than me in the next 12–24 months?
- ○ Could one contract, loan or dispute expose my personal savings?
- ○ Will an investor or customer specifically require a company?
- ○ Can I afford routine company secretarial, accounting and audit work?
- ○ Will I withdraw nearly all profit for household expenses, or reinvest it?
- ○ Have I compared my total tax position, not only headline rates?
- ○ If moving an existing business, have I planned assets, debts, contracts, GST and applicable tax relief?
If you answer yes to outside equity, co-founders or substantial enterprise-scale risk, a private limited company deserves serious consideration. If the business is solo, low-risk and early-stage, a proprietorship may still fit.
Getting started with TaxQue
Choose the structure because it fits your situation—not because every new business needs a company or because a proprietorship is always cheaper.
If you intend to start alone, explore proprietorship registration support. For company incorporation, see TaxQue's private limited company registration service and our company documents checklist. You can also compare an LLP, OPC and private limited company before deciding.
Explore business registration services
Official sources and further reading
- Ministry of Corporate Affairs — Companies Act, 2013 Official ↗ — company definitions, incorporation, governance and directors.
- MCA — SPICe+ and linked-filing FAQs Official ↗ — incorporation workflow.
- Income Tax Department — tax rates and rebates Official ↗ — individual tax regimes and eligibility.
- Income Tax Department — company concessional regime guidance Official ↗ — option and tax-rate conditions.
- Income Tax Department — Section 70 of the 2025 Act Official ↗ — business succession to a company.
- Income Tax Department — income-tax form FAQs Official ↗ — tax audit thresholds.
- GST Network — forms list, including ITC-02 Official ↗ — transfer of ITC when eligible.
- Ministry of MSME — official Udyam portal — free MSME registration.
Information checked for publication in October 2026. This is general guidance. Company-specific tax, licences, contracts and conversion terms require individual review.