
Running a business in your own name feels simple at the beginning. You can start selling, invoice customers and keep decisions in your own hands. But what happens when a large client asks for a company registration certificate, a co-founder wants a formal ownership stake, or an investor offers funding in exchange for shares?
That is when registering a private limited company becomes worth considering. It can separate the business from its owners, make share-based investment possible and give the business continuity beyond its founders. The trade-off is real, too: annual audits, ROC filings, record-keeping and professional fees continue even when business is slow.
This guide explains the benefits of registering a private limited company in India, where those benefits have limits, the likely costs and the steps to register through the Ministry of Corporate Affairs (MCA).
What exactly is a private limited company?
A private limited company is a separate legal entity incorporated under the Companies Act, 2013. Its Articles of Association restrict share transfers, membership is ordinarily limited to 200 (with statutory exclusions), and it cannot invite the public to subscribe to its securities. A conventional private limited company usually starts with at least two members and two directors; a One Person Company (OPC) is a separate single-member form.
The important point is that your company and you are not legally identical. The company can own assets, contract with suppliers, borrow and take legal action in its registered name. That separation creates advantages, but it also makes formal governance necessary.
Official reference: Companies Act, 2013 — India Code .
Six practical benefits of registering a private limited company
1. Limited liability can protect personal assets
Imagine two founders contribute ₹2 lakh each to a company. The business later fails with unpaid supplier bills. Ordinarily, their risk as shareholders is limited to their unpaid liability on shares rather than every rupee the company owes.
But limited liability is not a promise that personal property can never be at risk. A bank may ask founders for personal guarantees. Directors can also face liability under specific laws for fraud, wrongful conduct or statutory defaults. It is the legal separation, not absolute immunity, that makes this benefit valuable.
2. The company has its own legal identity
A customer signs with ABC Engineering Private Limited, not merely with its founder. The company can hold equipment, intellectual property, contracts and a bank account in its own name. This often makes it easier to organise business assets and obligations as the team grows.
A certificate of incorporation is useful evidence that the company exists. It does not, by itself, certify product quality, financial stability or government endorsement.
3. Bringing in investors becomes more structured
Suppose an investor offers ₹20 lakh for an ownership stake. In a company, the parties can negotiate share allotment, valuation, voting and other contractual rights, subject to applicable law and approvals. Raising investment is never automatic, but the share-capital framework provides a recognised mechanism.
Startups may also establish an employee stock option scheme (ESOP), subject to the Companies Act, relevant rules, approvals and tax considerations. That can help align employees with long-term business growth.
4. Ownership can be divided clearly between co-founders
Consider two co-founders who agree to a 60:40 split. Rather than relying on a verbal promise, the company can record their holdings in its share register, with rights supported by the Articles and a carefully drafted shareholders' agreement.
This becomes especially important when a founder leaves, a new partner joins, or someone wishes to sell shares. Transfers are still subject to the company's Articles and other applicable requirements.
5. The business can continue when owners change
A company's existence does not ordinarily end because a member dies, resigns or transfers shares. The succession or transmission of those shares follows the relevant legal documents and procedures, while the company continues to own its contracts and assets.
This is often called perpetual succession. It does not prevent dissolution or strike-off, but it avoids making the company's existence depend on one person's continued involvement.
6. Formal records can help with due diligence
Banks, enterprise customers and potential investors can inspect key public-company information through MCA services, such as the Corporate Identification Number (CIN), registered office and filing records. A formal structure can make due diligence easier.
That said, a private limited company is not guaranteed a loan, tender qualification or investor interest. Each counterparty makes its own decision on eligibility, security, financials and commercial suitability.
Private limited company benefits versus the responsibilities
| Potential advantage | What you must plan for |
|---|---|
| Separate legal entity | Company bank account, proper books and governance |
| Share-based funding | Valuations, approvals, filings and dilution |
| Limited liability | Personal guarantees and statutory director liabilities may still apply |
| Perpetual succession | Share-transfer, succession and register maintenance |
| Better due-diligence trail | Statutory disclosures and recurring ROC filings |
| Possible tax choices | Tax computation and eligibility review, not a guaranteed lower bill |
Registering a company does not automatically reduce tax or eliminate personal liability. Compare the full ownership, tax and compliance position before choosing a structure.
Is a private limited company taxed at 25.17%?
You will frequently see 25.17% described as the tax rate for private companies. That is one optional regime, not the universal rate applicable to every business.
Under Section 115BAA of the Income-tax Act, 1961, an eligible domestic company can opt for a base tax rate of 22%, with 10% surcharge and 4% health and education cess. The resulting effective rate is 25.168% (commonly rounded to 25.17%). The regime restricts specified deductions and incentives and ordinarily requires filing Form 10-IC within the prescribed time. Once validly exercised, the option generally cannot be withdrawn.
For example, on ₹10 lakh of taxable income under this simplified illustrative calculation:
| Component | Amount |
|---|---|
| Income tax at 22% | ₹2,20,000 |
| Surcharge at 10% of income tax | ₹22,000 |
| Cess at 4% of tax plus surcharge | ₹9,680 |
| Illustrative total | ₹2,51,680 |
This assumes the company validly opts for Section 115BAA and that ₹10 lakh is the taxable income after all applicable adjustments. It is not a tax quote for a particular company.
Companies outside this regime can have different rates depending on the law and their circumstances. Also, profits distributed as dividends are generally taxable in shareholders' hands; salary received by a director has its own tax treatment. It is misleading to compare 25.17% directly with an individual's highest slab rate without examining withdrawal of profits, deductions and other taxes.
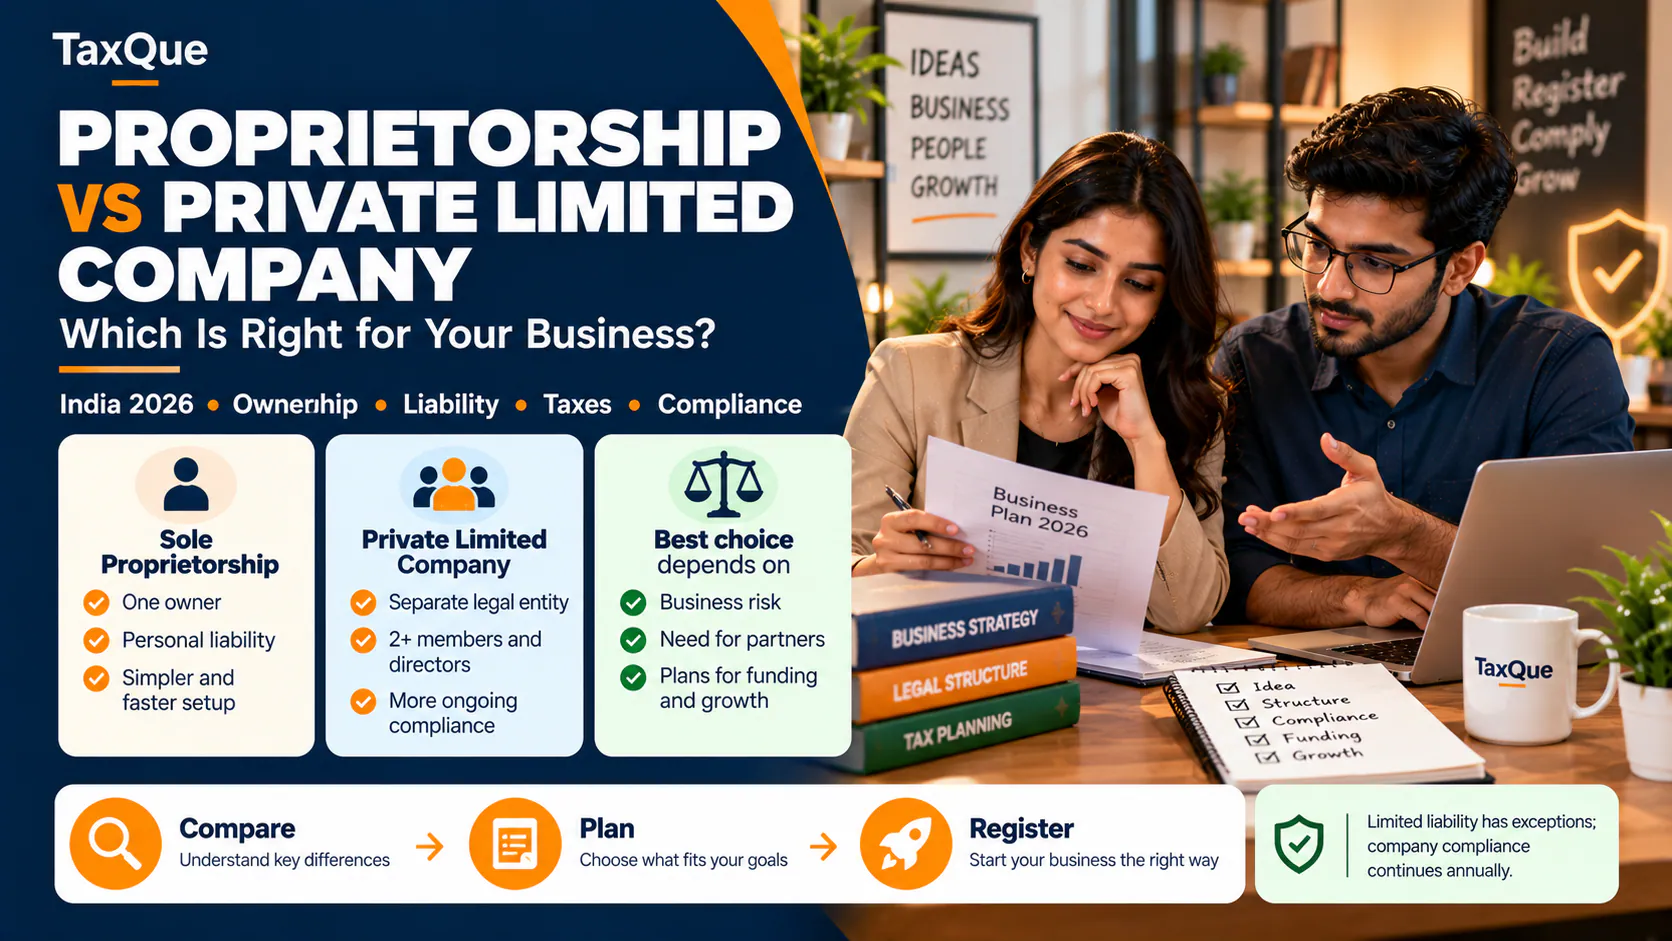
See the Income Tax Department's domestic company tax guide Official ↗ and Form 10-IC user manual Official ↗. For a broader comparison read proprietorship versus private limited company.
Can a startup claim a three-year income-tax holiday?
Eligible startups may obtain a 100% profit-linked deduction for three consecutive years within the first ten years, under Section 80-IAC, subject to the prescribed conditions and approval. DPIIT recognition alone does not guarantee the deduction. Eligibility and Inter-Ministerial Board certification must be examined.
Importantly, a company opting for Section 115BAA cannot simultaneously claim certain incentives, including Section 80-IAC. Assess both routes before exercising a tax option.
Official references: Startup India 80-IAC guidance Official ↗ and CBDT clarification Official ↗.
What does a private limited company cost each year?
Incorporation is a one-time process, but compliance is recurring. A company with no revenue may still have annual filings, audit and other obligations. Fees differ by state, authorised capital, activity, number of transactions and the work required from professionals; any flat price quoted without those inputs is only an estimate.
| Compliance item | Typical requirement or trigger |
|---|---|
| Statutory audit | Annual audit of company financial statements under company law |
| Financial statements | Applicable AOC-4 family filing with ROC |
| Annual return | Applicable MGT-7 or MGT-7A filing |
| Board meetings and minutes | Frequency depends on whether small-company exemptions apply |
| Income-tax return | Applicable company return; tax audit is a separate test |
| TDS / GST / payroll | Only when the relevant law and transactions trigger them |
| Statutory records | Registers, resolutions and required company records |
A statutory audit under the Companies Act is distinct from a tax audit under income-tax law. A company can need the former even when it does not meet the threshold for the latter.
For details see private limited company annual compliance.
Small company status may reduce some compliance
The notified small-company financial ceilings were increased with effect from 1 December 2025 to ₹10 crore of paid-up share capital and ₹100 crore of turnover, subject to Section 2(85) and statutory exclusions. Both financial conditions and the exclusion rules matter: holding or subsidiary companies, Section 8 companies and certain specially governed companies are not eligible merely because they are below the ceilings.
Eligible small companies may use the simplified annual return in MGT-7A and certain exemptions, including reduced board-meeting frequency under the relevant provisions. A small company is not exempt from statutory audit merely because it is small.
Private limited company, LLP, OPC or proprietorship: which suits you?
| Situation | Structure worth considering | Reason |
|---|---|---|
Solo freelancer testing a low-risk service | Proprietorship | Simple administration, but no separate corporate liability shield |
One owner seeking corporate form | OPC | Company status with one member, subject to OPC rules |
Two professionals wanting a partnership-style setup | LLP | Separate legal entity with LLP governance and tax treatment |
Founders planning equity funding or ESOPs | Private limited | Recognised share-capital and employee-equity framework |
Business planning public securities offers | Public company | Separate legal and securities-law requirements apply |
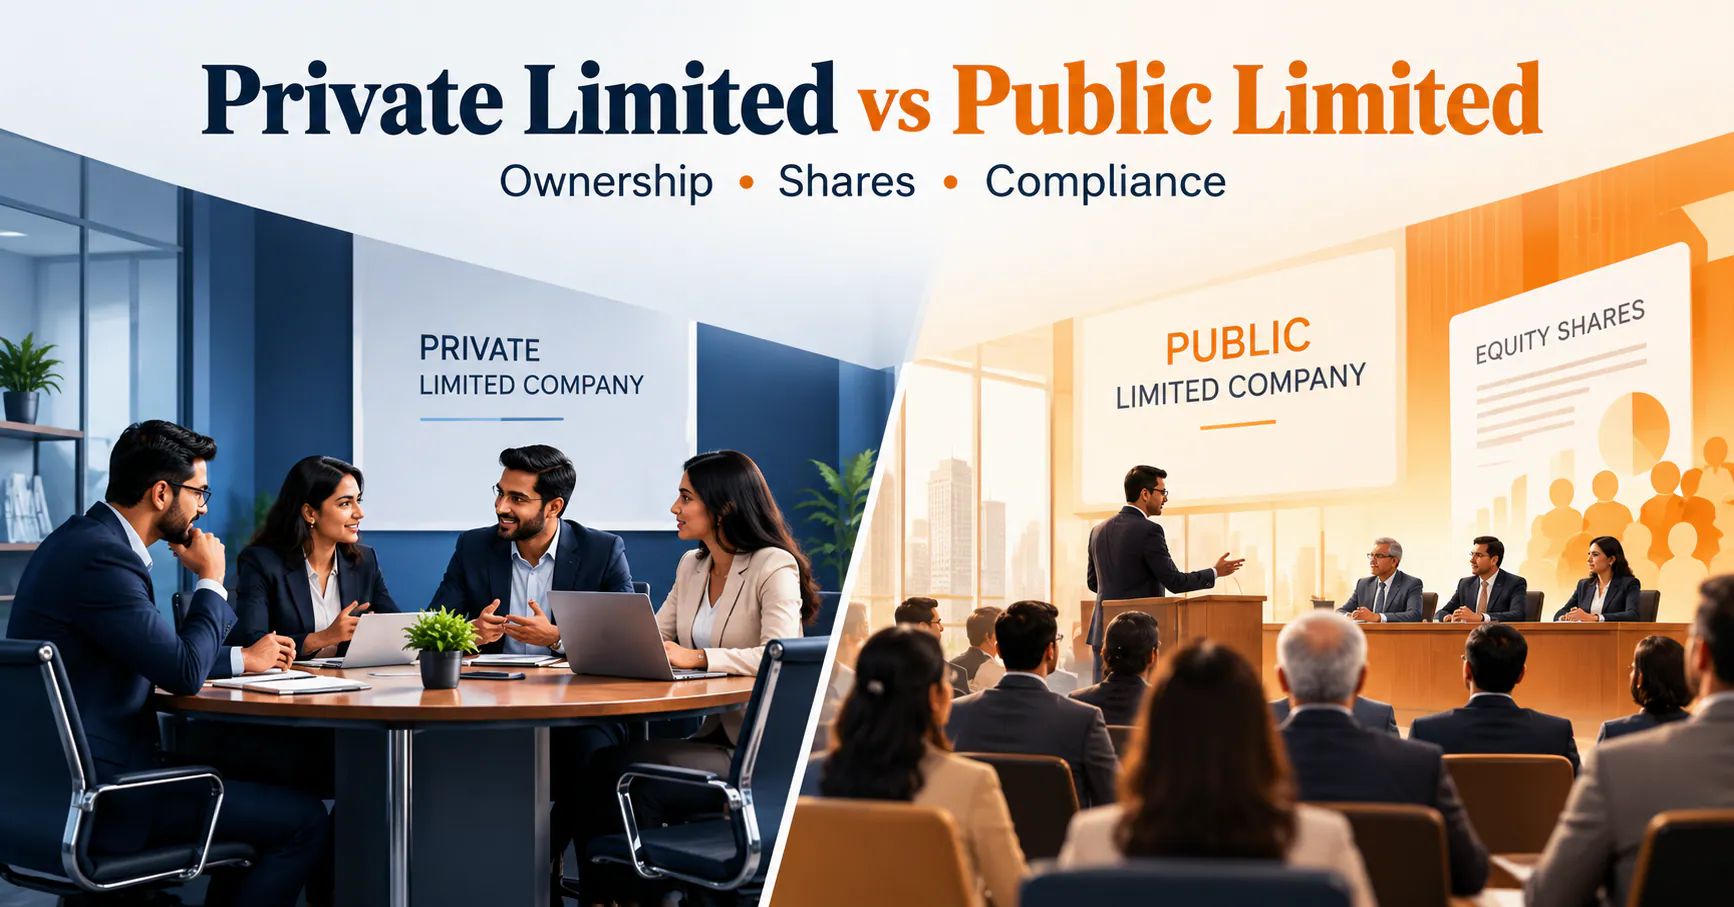
There is no one structure that is best for every founder. A small consultancy may prioritise simplicity, while a product startup with investors may place greater weight on equity fundraising. Compare private limited, LLP and OPC structures and private versus public company.
Documents needed before registering a private limited company
Use this working checklist and confirm any case-specific requirements on the MCA portal:
- Proposed company names and main business activities
- PAN and acceptable identity/address proof for subscribers and directors
- Digital Signature Certificates (DSCs) for persons signing electronic forms
- Registered office address, recent utility evidence and owner consent/NOC where relevant
- Proposed share capital, shareholding division and director details
- Memorandum of Association (MOA), Articles of Association (AOA) and required declarations
- Professional or sectoral approvals where the proposed activity requires them
The same two people can generally be shareholders and directors. At least one director must meet the statutory resident-director test under Section 149(3); that rule should not be reduced to a casual requirement that the person simply has an Indian address.
How to register a private limited company through MCA SPICe+
Incorporation process
-
Choose the structure
Confirm shareholders, directors, ownership split, business objects and proposed capital.
-
Prepare DSCs and records
Collect identity, address and registered-office documents and arrange electronic signing.
-
Check and reserve the name
Use MCA SPICe+ Part A, subject to name-availability and naming rules.
-
Prepare incorporation forms
Complete SPICe+ Part B and applicable linked e-MOA, e-AOA, INC-9 and AGILE-PRO-S filings.
-
Submit and pay fees
Review the forms, affix required signatures, upload and pay applicable MCA and state stamp-duty charges.
-
Receive incorporation records
On approval, obtain the certificate of incorporation and allotted identifiers such as CIN, PAN and TAN.
-
Complete post-incorporation actions
Check commencement-of-business requirements (including INC-20A where applicable), share certificates, auditor appointment, statutory registers and recurring filings.
MCA's AGILE-PRO-S process integrates registrations and applications such as EPFO, ESIC and bank-account opening; GST is optional where the relevant conditions are met. A registration number does not necessarily mean every ongoing labour-law filing becomes due immediately—applicability depends on the governing law.
Official reference: MCA SPICe+ incorporation FAQs Official ↗. Also see private limited company registration costs.
Mistakes to avoid after incorporation
A new company can fall behind on compliance even before it starts earning revenue. Common mistakes include:
- Mixing founders' personal money with company receipts and payments without proper accounting.
- Forgetting that statutory audit and ROC filings may apply even if sales are nil.
- Assuming shareholders can take company profits home without considering salary, dividend, loan and tax rules.
- Issuing shares or bringing in investors without the required approvals, valuation review and filings.
- Missing commencement, share-certificate, auditor and other post-incorporation deadlines applicable to the company.
- Relying on an old blog for fees, tax rates, board-meeting rules or due dates.
Before accepting an investor's money or choosing a tax regime, ask your accounting and legal advisers to review the actual facts. A short review early on can prevent a much more expensive correction later.
Is your business ready? A five-question self-check
- ○ Do you need co-founders' shareholdings documented clearly?
- ○ Are you planning to attract equity investors or offer an employee equity plan?
- ○ Would a separate legal entity make your contracts and assets easier to manage?
- ○ Can you budget for annual audit, filings, accounting and professional support?
- ○ Have you compared the total tax and cash-withdrawal consequences with an LLP or proprietorship?
If you answer yes to the first three but cannot yet manage the fourth, address that gap before incorporation. The purpose of a company is not simply to obtain a certificate; it is to maintain a workable legal structure as the business develops.
The bottom line
A private limited company can provide limited liability, continuity, structured ownership and a credible route to equity funding. Those benefits come with recurring statutory responsibilities that should be budgeted from day one.
If you're planning to incorporate, compare the company's capital needs, co-founder arrangements, liability exposure, likely tax position and compliance workload—not just the registration quote. TaxQue can help you understand the incorporation steps and related compliance services before you decide.
Explore TaxQue private limited company registration or contact the team.
Primary sources and further reading
- Companies Act, 2013 — India Code
- MCA SPICe+ incorporation FAQs Official ↗
- Income Tax Department — Domestic company taxation Official ↗
- Income Tax Department — Section 115BAA / Form 10-IC Official ↗
- Startup India — Section 80-IAC Official ↗
Editorial review date: 16 October 2026. Verify case-specific thresholds, filing requirements, professional fees and operative notifications when taking action.