If you have recently changed jobs, lost your job, or need money for an urgent expense, your EPF balance may look like savings you can withdraw at any time. It does not work quite like a bank account. How much you can withdraw depends on the type of claim, your membership, and why you are leaving or applying.
The good news is that EPFO has simplified online claims. The less obvious part is that partial PF withdrawals, final PF settlement and Employees' Pension Scheme (EPS) withdrawal are three different things. Choosing the wrong one can result in a rejection or an unnecessary wait.
This guide explains the EPF Scheme, 2026, notified on 29 June 2026; the online claim procedure; the 25% minimum-balance rule; when a 12-month or 36-month wait matters; and how to check your claim. Start by choosing your situation, not by guessing the form.
Quick answer: Log in at the official EPFO Member Portal Official ↗, verify your UAN, Aadhaar, bank and service information, select Online Services → Claim, choose the eligible claim type, and authenticate as directed. Do not share an Aadhaar OTP, UAN password or bank details with anyone offering to “speed up” the claim.
EPF withdrawal rules in 2026: what changed?
The Employees' Provident Funds Scheme, 2026 replaced the 1952 scheme with effect from its Gazette publication on 29 June 2026. The changes streamline advance withdrawals but also protect a part of members' savings. The Ministry of Labour and Employment explained the withdrawal-policy changes in its 13 October 2025 and 15 October 2025 communications.
| Question | Current rule or practical answer |
|---|---|
| What partial-withdrawal categories exist? | Essential needs, housing needs and special circumstances. |
| Minimum membership for the ordinary partial-withdrawal categories? | Generally 12 months; an important exception applies when someone exits employment before completing 12 months. |
| How much is protected? | A minimum balance equal to 25% of aggregate eligible member and employer contributions and interest must normally remain for partial withdrawals. |
| Can I take the entire eligible amount for a particular purpose? | Up to 100% of the eligible member balance, not 100% of the entire PF account; purpose and frequency conditions apply. |
| Lost my job? | EPFO's policy communication says up to 75% may be accessed immediately; ordinary full settlement after cessation of covered employment generally requires 12 months without covered employment. |
| Does everyone wait 12 months for final settlement? | No. Retirement and certain special grounds have distinct rules under Paragraph 49. |
| What about EPS pension withdrawal benefit? | It follows the separate Employees' Pension Scheme, 2026; generally 36 months from the last contribution due, or reaching superannuation, whichever comes first, for an eligible early leaver. |
A 75% accessible share and a 25% retained minimum are not always the same as an immediately payable claim. EPFO checks the purpose, remaining eligible balance, service history and other Scheme conditions.
Three types of EPF claims: choose the right one
1. Partial withdrawal or PF advance (Form 31)
Use this where you want to take some savings without closing your EPF membership. The 2026 rules group requests into essential needs, housing needs and special circumstances. A partial withdrawal is not a loan that you repay, but it reduces the balance that may continue earning EPF interest.
2. Final PF settlement (Form 19)
This is for getting the remaining provident-fund accumulation when legally payable. Simply resigning and immediately joining another covered employer generally points towards transferring the old balance, not applying for final settlement. A retirement, permanent disability, qualifying retrenchment, permanent migration abroad or other specified ground may have a separate entitlement.
3. EPS withdrawal benefit or Scheme Certificate (Form 10C, as applicable)
EPS is the pension component, not another balance inside the EPF passbook available on demand. For a member leaving with insufficient eligible pension service, the EPS 2026 framework provides a withdrawal benefit or, where eligible, a Scheme Certificate preserving service. Members who qualify for a pension should review pension entitlements rather than assuming they can withdraw an EPS balance in cash.
See the official EPFO claim-form overview Official ↗.
Before you withdraw: UAN and KYC checklist
- ○ Your UAN is active and you can sign in to the official Member Portal.
- ○ Aadhaar is correctly linked and verified; your Aadhaar-linked mobile can receive OTPs.
- ○ Your bank account and IFSC are correctly seeded and verified in EPFO records.
- ○ Your name, date of birth and other identity details agree across Aadhaar, UAN and bank records.
- ○ PAN is linked where relevant, especially to avoid complications with tax deduction on taxable final settlements.
- ○ Your date of joining, date of exit and service history are correct for the type of claim being made.
- ○ You have checked the passbook and the latest employer contributions.
- ○ You understand whether you need an advance, final settlement, EPS benefit or a PF transfer.
What changed with document uploads? EPFO announced on 3 April 2025 that an image of a cancelled cheque or attested passbook is no longer required for online claims. It also removed the general employer-approval step for seeding a bank account once the bank has verified it. Other identity or service-record corrections can still require additional verification, so follow any specific document request actually displayed in your claim.
If you cannot activate or access your UAN, EPFO's live Member Portal directs members to use the UMANG app's Aadhaar face-authentication functionality for UAN generation or activation. Our UAN password reset guide covers access problems.
Partial EPF withdrawal in 2026: categories, eligibility and limits
Essential needs: illness, education and marriage
Under Paragraph 46 of the EPF Scheme, 2026, eligible essential-needs advances cover illness of the member or family members, education and marriage. Education withdrawals may be taken up to 10 times during membership and marriage withdrawals up to 5 times, subject to the rule and available balance. The ordinary service requirement is 12 months.
Housing needs: purchase, construction, loan repayment and renovation
The 2026 housing category includes buying a house or flat, buying a site for house construction, building a house, repaying an eligible housing loan, and additions or improvements. The Scheme permits no more than five such partial withdrawals over the membership period, subject to eligibility and balance conditions. Confirm that the particular housing choice displayed by EPFO matches your actual purpose.
Special circumstances: a different evidence model
The simplified special-circumstances category allows certain partial withdrawals without having to establish the older list of specific events. Paragraph 46 permits up to two special-circumstances partial withdrawals in one financial year, normally after 12 months of total membership. A self-declaration is not permission to select false details or overstate eligibility.
Exception if you leave a job before 12 months of EPF membership
One point often missed in short blog posts is Paragraph 46(5): it separately provides for a member exiting employment before completing 12 months of membership to seek a partial withdrawal, limited to the eligible member balance. That is not a rule allowing every active member to withdraw before 12 months. The exact eligibility and options presented by the portal matter.
Official explanation: PIB's 2025 withdrawal reform brief ; notified EPF Scheme, 2026, Paragraph 46 (reproduced text) .
How does the 25% minimum balance work? A calculation
Suppose your eligible EPF account accumulations are ₹4,00,000, comprising the relevant employee and employer shares and interest. Assume no previous partial withdrawal affects the example.
Illustrative PF balance
Total considered balance
₹4,00,000
Employee + employer portions and interest, as assumed
Protected minimum balance (25%)
₹1,00,000
Normally retained for partial withdrawal
Indicative eligible member balance
₹3,00,000
Maximum potential base, not an approved claim
A member may be able to request a partial withdrawal up to ₹3 lakh where the applicable purpose, service and frequency rules permit. This does not mean that everyone with ₹4 lakh may immediately take ₹3 lakh. EPS funds are separate; the eligible balance may also be affected by the member's actual account details and earlier withdrawals.
EPF withdrawal after leaving a job: 75%, 12 months and exceptions
A common situation is losing a job and needing money before finding another. The Labour Ministry's October 2025 clarification said members could access 75% after unemployment, while ordinary premature full PF settlement would be available after one year. Paragraph 49(2) of the notified 2026 EPF Scheme requires a continuous period of at least 12 months without employment in an establishment covered by the Code for general full withdrawal.
But the one-year rule is not universal. Paragraph 49(1) provides distinct grounds for full withdrawal, including retirement after attaining 55, permanent and total incapacity, permanent migration abroad, qualifying retrenchment and specified voluntary retirement circumstances. Other limited exceptions and waiting conditions exist. Paragraph 49(2) also contains a specific exception for female members resigning for marriage.
Do not assume that selecting “unemployed” on the portal automatically qualifies you for full settlement. Check your actual date of exit, other employment and the statutory condition for your claim.
Should you withdraw PF when joining a new company?
If you move from one covered employer to another, transferring EPF normally preserves retirement savings and helps establish continuity of service for income-tax purposes. Use the transfer workflow rather than a final-withdrawal claim where a transfer is appropriate. Read EPF balance check and see EPFO's April 2025 transfer simplification .
EPS pension withdrawal is different: the 36-month rule
The Employees' Pension Scheme, 2026 is separately notified under G.S.R. 527(E), and it must not be confused with PF withdrawal under G.S.R. 525(E). For an otherwise eligible member leaving before pension eligibility, Paragraph 13 generally allows a withdrawal benefit after 36 months from the date the last contribution became due, or at superannuation, whichever is earlier, with the Scheme Certificate option subject to its conditions.
If you have 10 years or more of eligible pension service, a Scheme Certificate or pension option can be more relevant than a pension withdrawal benefit. Always look at EPS service history and pension eligibility independently of the PF amount in your passbook.
Source: Employees' Pension Scheme, 2026, Gazette-based Paragraph 13 and Ministry of Labour & Employment explanation .
How to apply for EPF withdrawal online: step by step
Apply through the official EPFO Member Portal
-
Open the Member Portal
Sign in at unifiedportal-mem.epfindia.gov.in/memberinterface with your UAN, password and captcha. Use official EPFO links only.
-
Check KYC and service
Review Aadhaar verification, verified bank account, PAN where relevant, employment dates and passbook balances.
-
Choose the claim service
Go to Online Services and open the Claim/online claim option available in your account. The exact menu may change after portal upgrades.
-
Verify your bank
Confirm the linked bank account as the portal requests; do not submit someone else's account.
-
Select the correct claim
Choose the eligible PF advance (Form 31), final settlement (Form 19), or pension-related claim (Form 10C) displayed, and supply the requested claim purpose and amount.
-
Review before submitting
Check all declarations, account details and eligibility notes. Don't assume the full passbook amount is withdrawable.
-
Authenticate and save acknowledgement
Complete the Aadhaar OTP or other official authentication offered and save the claim receipt or claim reference number.
-
Track its progress
Check claim status in the member portal or EPFO Passbook & Claim Status service, and respond to any valid EPFO request.
Open official EPFO Member Portal
You can also check eligible EPFO services in the UMANG ecosystem . Never pay an unofficial agent to submit an ordinary online claim. EPFO specifically cautions against unauthorised intermediaries and fake portals.
How long does PF withdrawal take in 2026?
| Type of claim | What you can reasonably expect |
|---|---|
| Eligible auto-settled advance, up to ₹5 lakh | EPFO has said these can be processed within about three days, after system checks. Not every claim qualifies. |
| Other complete PF claims | Paragraph 54 of the 2026 Scheme provides a 20-day period for settlement/payment of complete claims or communication of deficiencies. |
| Claim rejected or returned for deficiency | Correct the specific problem; a new or corrected claim may need fresh processing. |
| Claim marked “Settled” but not credited | Check the registered bank account and payment status before raising a grievance. |
The ₹5 lakh limit is an auto-settlement threshold, not permission to withdraw ₹5 lakh regardless of eligibility. EPFO confirmed the enhanced limit in its 24 June 2025 release .
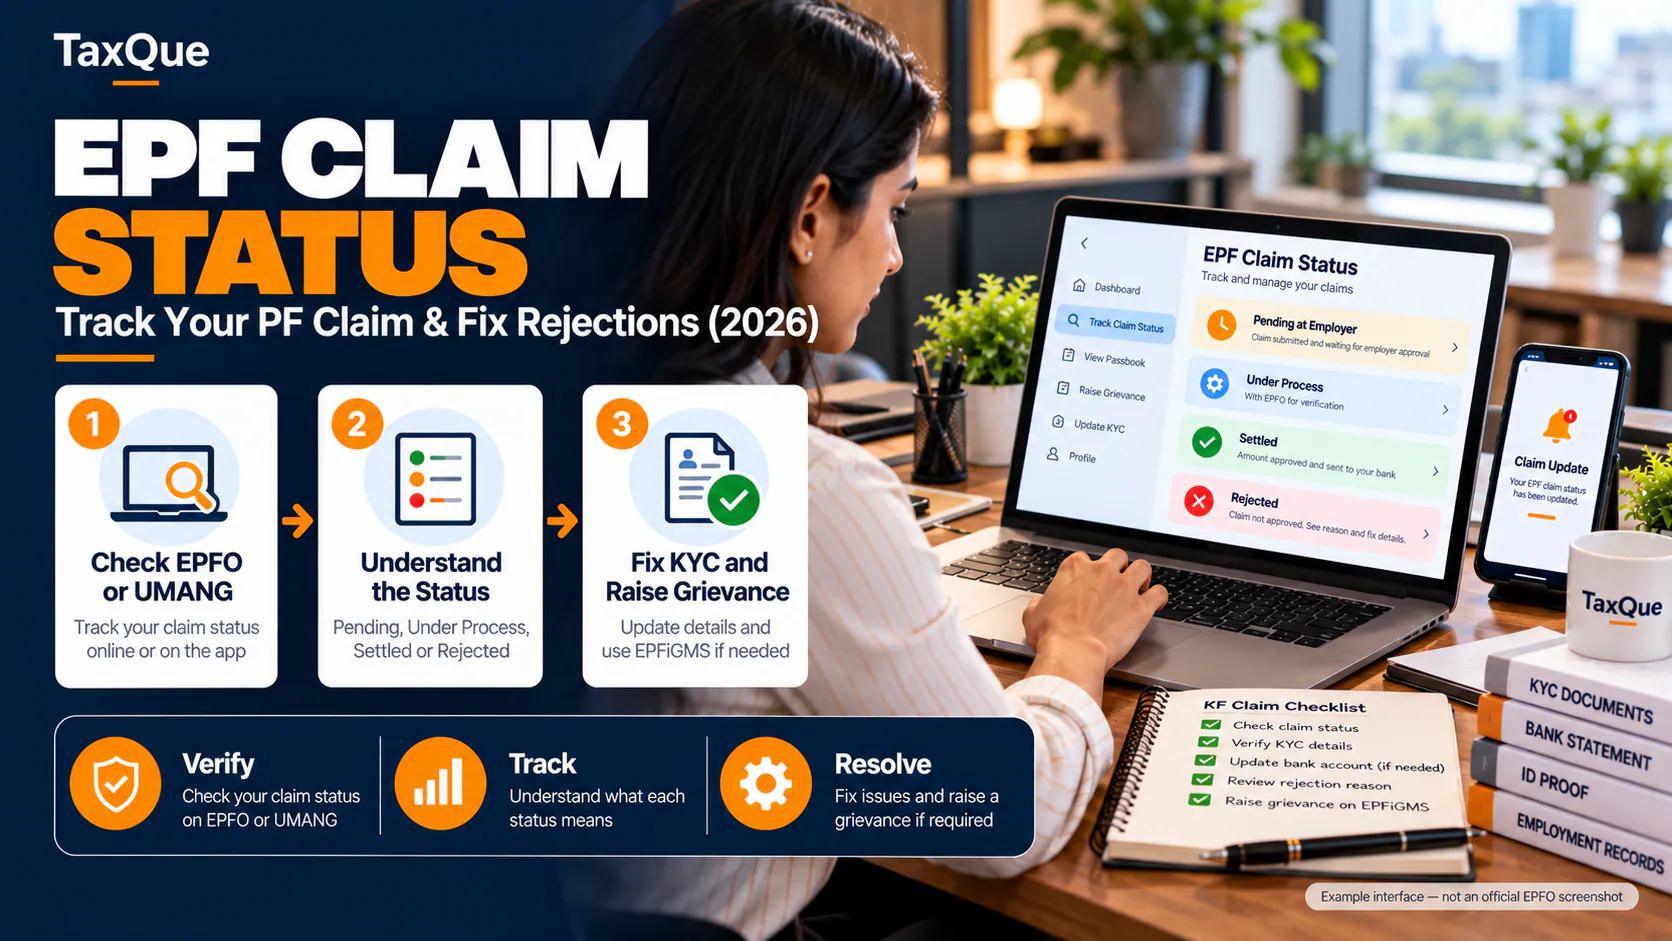
How to track PF withdrawal status and fix a rejection
Open the EPFO Passbook & Claim Status portal Official ↗ or use your Member Portal claim history. Keep your claim reference number and UAN handy; never share passwords or OTPs.
| Status or problem | What to do next |
|---|---|
| Under process | Allow processing time and check if a new request appears in your account. |
| Rejected due to Aadhaar/name mismatch | Correct identity records through the appropriate EPFO member-data correction route. |
| Wrong bank details | Update and reverify bank seeding, then follow instructions for filing again. |
| Date of exit missing | Review service history and request correction or use the permitted member route. |
| Claim type or amount not eligible | Compare the reason against the specific EPF/EPS provisions; do not repeatedly submit the same ineligible claim. |
| Settled but no credit | Verify the account, payment reference and bank statement; escalate if necessary. |
For a claim that remains unresolved beyond the relevant service period, use the official EPFiGMS grievance portal and attach the claim acknowledgement and rejection or payment details. For more detail, see EPF claim status and rejection guide.
Is EPF withdrawal taxable? Five-year rule and TDS
Withdrawal eligibility is not the same as tax exemption. Under Paragraph 8 of Part A of Schedule XI of the Income-tax Act, 2025, the accumulated balance of a recognised provident fund is generally excluded from taxable income after five years or more of continuous service. Certain earlier withdrawals can also qualify for relief, such as service ending because of ill-health, employer closure or another cause beyond the employee's control; qualifying transfers preserve continuity.
A premature taxable final withdrawal can have multiple tax components, and TDS may apply depending on the accumulated amount, the statutory threshold, PAN and the relevant year. The familiar ₹50,000 threshold and 10% rate appear in the Income Tax Department's rules for AY 2026–27 under the 1961 Act, but for withdrawals paid from 1 April 2026, use the corresponding withholding provisions of the Income-tax Act, 2025 (including Section 393) and current rates, rather than blindly copying an old section number.
Also remember that EPF advances, recognised-fund accumulations and the EPS withdrawal benefit are not automatically taxed in the same way. Before relying on an exemption or submitting Form 15G/15H, check the taxpayer's age, other income, service continuity and the latest guidance.
Sources: Income-tax Act, 2025 — Schedule XI Official ↗, Section 191 Official ↗, and Income Tax Department withholding transition FAQ Official ↗.
Common EPF withdrawal mistakes to avoid
- Trying to withdraw all funds after moving directly to another EPF-covered employer rather than checking transfer eligibility.
- Confusing 75% of eligible funds with 75% of every figure shown in the passbook.
- Assuming the 12-month condition has no exception, or assuming every exception applies to everyone.
- Treating EPF and EPS as a single account with a single withdrawal deadline.
- Applying again after rejection without fixing a mismatch in bank, Aadhaar or date-of-exit records.
- Looking for a cancelled-cheque upload field that EPFO removed from the normal online claim flow in 2025.
- Giving a third party a UAN password or Aadhaar OTP to “complete” the claim.
- Believing a quick auto-settlement announcement guarantees every PF claim will be paid in three days.
Final checklist: withdraw only the amount you're eligible for
Start with your reason for withdrawing. If you need an advance while employed, read the purpose and eligibility conditions. If you have left employment, check whether your circumstances allow a partial withdrawal, the 12-month final-settlement route or one of its exceptions. Then check EPS separately.
Most avoidable delays come from incorrect service data, bank verification, selecting the wrong claim or overlooking a portal message. Download your passbook and review the application carefully before submitting.
If you're an employer trying to prevent PF problems for your staff, TaxQue's PF return filing and compliance service supports monthly contributions and record consistency. Employees should use the official EPFO portal for their individual withdrawal claims, which can be submitted without an outside agent.
Explore TaxQue PF compliance services
Official references and publication checks
- Ministry of Labour — EPF withdrawal reform, 13 October 2025
- Ministry of Labour — withdrawal FAQs and examples, 15 October 2025
- Employees' Provident Funds Scheme, 2026 — G.S.R. 525(E), reproduced legal text
- Government confirmation of the 2026 notified Scheme
- EPFO online claims: removal of cheque/passbook uploads
- EPFO advance-claim auto-settlement up to ₹5 lakh
- EPFO Member Portal Official ↗
- EPFO Passbook & Claim Status Official ↗
- Income-tax Act, 2025 — Schedule XI Official ↗
Editorial verification date: 18 October 2026. Portal labels, procedural screens and conditions can change; check the official service before filing.