Everyone needs these
- PAN, linked with your Aadhaar. If PAN is inoperative because it isn't linked, refunds are held back.
- Aadhaar, for e-verification by OTP.
- Annual Information Statement (AIS) and Taxpayer Information Summary (TIS), from the e-filing portal under Services → AIS. They show the income the department already knows about: salary, interest, dividends, share and mutual fund sales, large transactions.
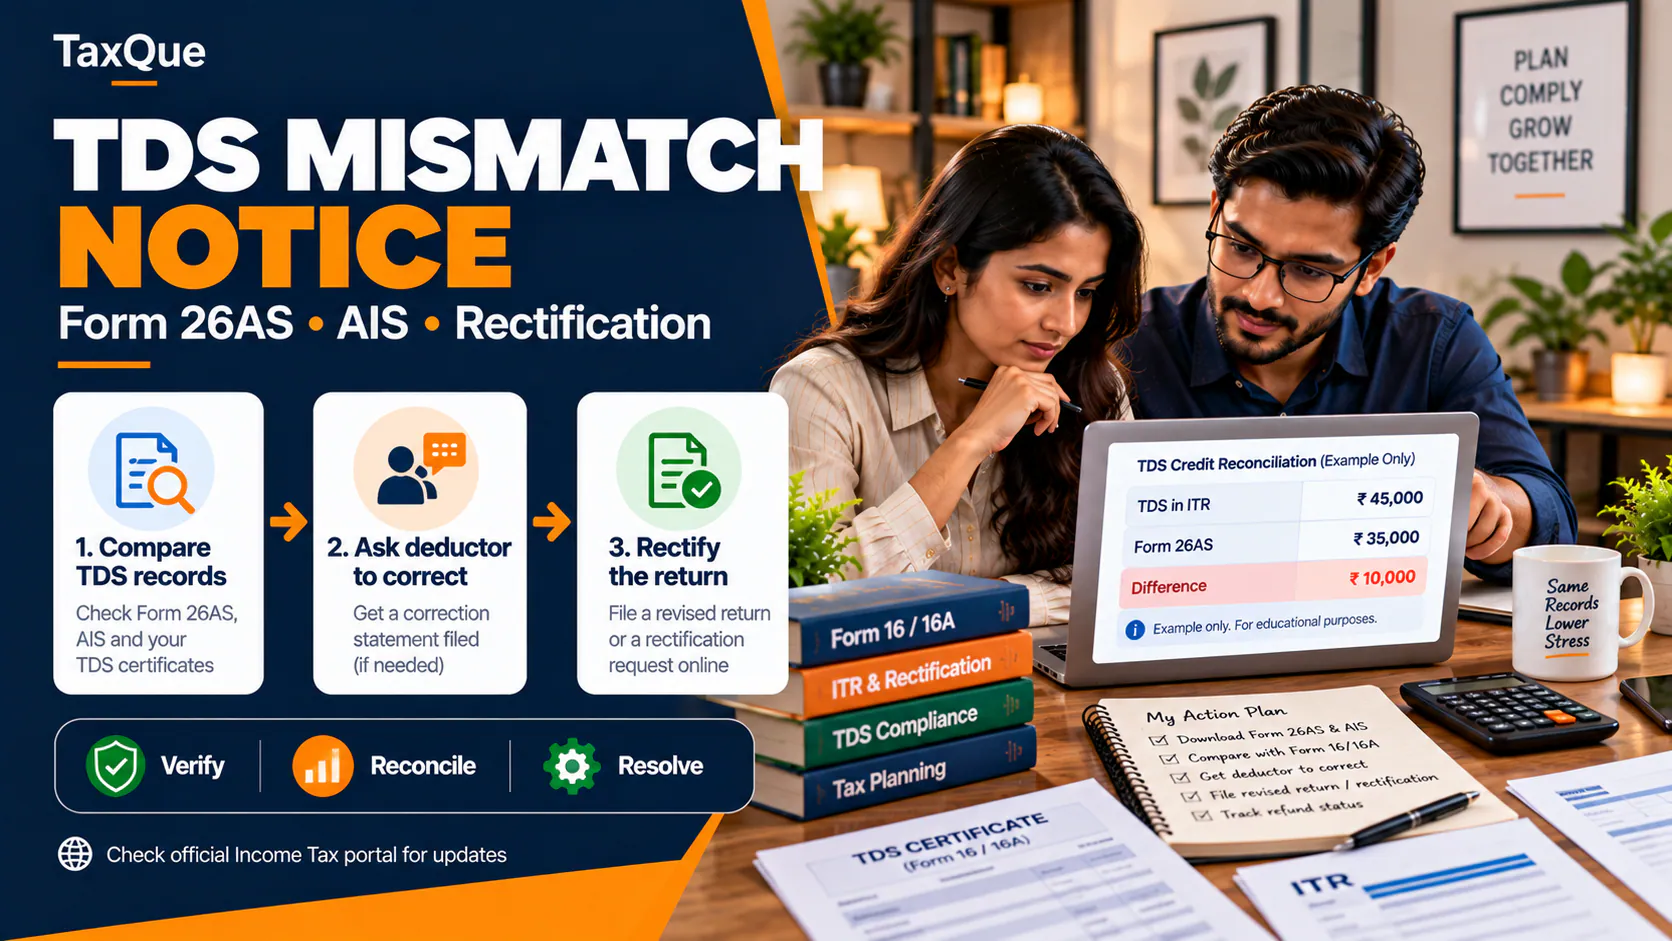
- Form 26AS: TDS and TCS credited against your PAN, and any advance or self-assessment tax paid.
- Bank account details for every account you held. The one for your refund must be pre-validated on the portal.
Start with the AIS. Anything it shows that you leave out of your return is the most common reason for a notice.
Documents by type of income
| Income | Documents |
|---|---|
| Salary or pension | Form 16 from each employer (issued by 15 June), salary slips, Form 12BA for perquisites if any |
| Interest | Interest certificates from banks and post office, including savings and FD interest |
| House property | Rent received; for a home loan, the lender's certificate splitting interest and principal |
| Shares and mutual funds | Capital-gains (tax P&L) statement from your broker; capital-gains statement for mutual funds from CAMS / KFintech or MF Central |
| Property or other assets sold | Sale deed, purchase deed and cost-of-improvement bills |
| Business or profession | Profit and loss account and balance sheet (or turnover and bank records for presumptive income), GST returns if registered, Form 16A for TDS on receipts |
| Foreign income or assets | Foreign bank and investment statements, Form 67 if claiming foreign tax credit |
Deduction proofs: only if you choose the old regime
The new tax regime is the default and allows few deductions. For FY 2025-26 it gives a standard deduction of ₹75,000 to salaried people and pensioners, and a rebate that brings the tax to nil on income up to ₹12 lakh (not counting special-rate income such as capital gains).
If you opt for the old regime, keep proofs for what you claim:
- Section 80C (up to ₹1.5 lakh): PPF, ELSS, life insurance premium, tuition fees, home-loan principal, EPF.
- Section 80D: health insurance premium receipts.
- HRA: rent receipts and the rent agreement. You also need the landlord's PAN if the rent is over ₹1 lakh a year.
- Home-loan interest: the lender's interest certificate.
- Section 80G: donation receipts with the charity's registration number.
- Section 80E: education-loan interest certificate.
Employer contributions to NPS (section 80CCD(2)) are allowed under both regimes.
Which ITR form do you need?
| Form | For |
|---|---|
| ITR-1 (Sahaj) | Resident individuals with income up to ₹50 lakh from salary or pension, house property, interest and other sources, and small long-term gains on listed shares or equity funds (up to ₹1.25 lakh) |
| ITR-2 | Individuals and HUFs with capital gains beyond ITR-1's limits, foreign income or assets, or income over ₹50 lakh, but no business income |
| ITR-3 | Individuals and HUFs with income from a business or profession |
| ITR-4 (Sugam) | Residents with presumptive business or professional income and total income up to ₹50 lakh |
Deadlines and what happens if you are late
- Missed the original due date for FY 2025-26? You can still file a belated return until 31 December 2026. The late fee is up to ₹5,000, or ₹1,000 if total income is ₹5 lakh or less, plus interest on any tax due. Some losses cannot be carried forward from a belated return.
- After that, an updated return (ITR-U) can be filed within 48 months of the end of the assessment year, with additional tax.
- Whatever you file, e-verify it within 30 days. Until then it isn't treated as filed.
Coming up: the Income-tax Act, 2025 applies from 1 April 2026, so from the 2026-27 tax year several forms are renumbered. Form 16, for example, becomes Form 130. Returns for FY 2025-26 are still filed under the old Act.
Prefer to hand it over? TaxQue's income tax return filing service checks your documents against your AIS before filing.