
A notification from the Income Tax Department can be worrying, especially when it says your return has been selected for scrutiny. You may have already received a refund, matched your Form 26AS and filed everything on time. Does a scrutiny notice mean the department has found tax evasion?
No. A notice under Section 143(2) means the department wants to examine the accuracy of a filed return and may ask for evidence. It is not, by itself, a finding that you concealed income or owe additional tax. But the notice has a response deadline, and ignoring it can seriously weaken your position.
This guide explains how to verify a scrutiny notice, calculate the statutory notice window, respond through the Income Tax e-filing portal, organise evidence and deal with an assessment order. It also explains the 2026 change in income-tax legislation—because a 143(2) notice for AY 2026–27 does not automatically become a notice under the 2025 Act.
Received a notice today? Download the complete PDF from the official portal, check the assessment year, DIN, issue/service details and reply deadline, then begin preparing the documents requested. The date shown on your notice controls your immediate response; do not rely on a generic “15-day” rule.
What is a scrutiny notice under Section 143(2)?
For assessment years governed by the Income-tax Act, 1961, Section 143(2) allows the department to examine a return more closely when it considers verification necessary. The subsequent scrutiny assessment is generally made under Section 143(3). It may examine income reported, claims for deductions, capital gains, losses or other aspects of the return relevant to the proceeding.
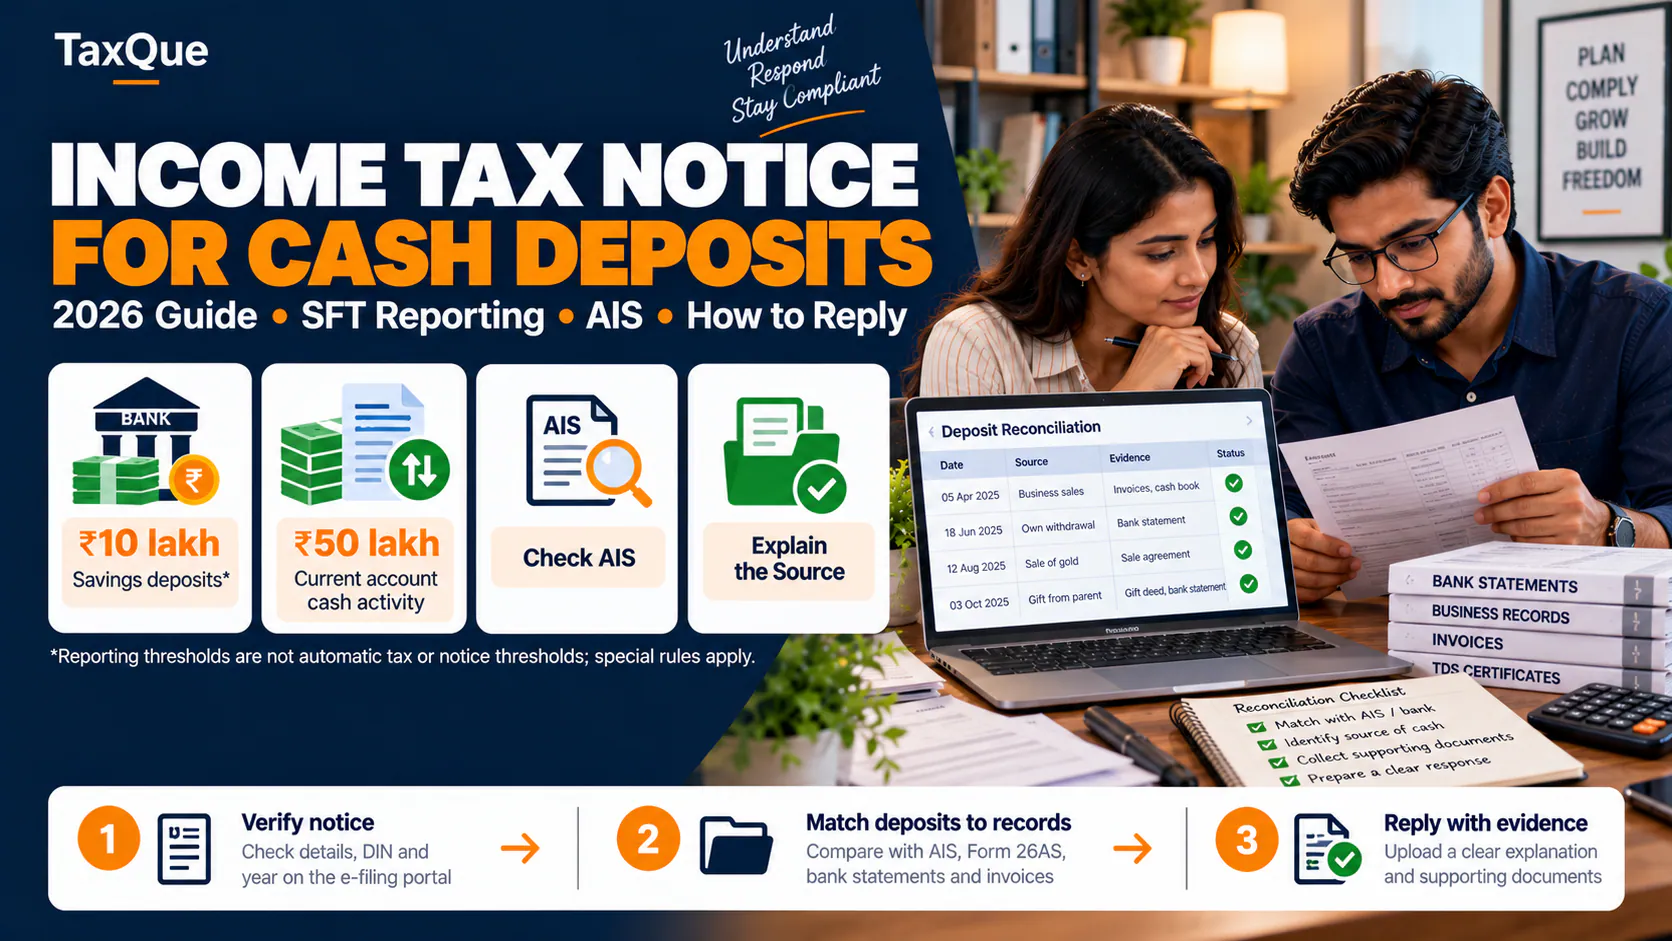
For example, a taxpayer reports a large bank deposit but shows only a modest amount of taxable income. There may be a perfectly valid explanation: the deposit could represent a loan repayment, sale proceeds or transfers between accounts. The department may nevertheless ask for supporting records. A careful reply connects each transaction to reliable evidence.
A scrutiny case is different from a simple return-processing intimation and from a reassessment of income believed to have escaped assessment. Check the section number and assessment year before choosing how to respond.
Which law applies after 1 April 2026?
| Period being examined | Relevant legal framework | Scrutiny reference |
|---|---|---|
FY 2025–26 / AY 2026–27, and earlier assessment years | Income-tax Act, 1961 continues to govern those proceedings under the transition rules | Section 143(2) notice; Section 143(3) assessment |
Tax Year 2026–27 (income earned 1 April 2026–31 March 2027), and later | Income-tax Act, 2025 | Section 270(8) scrutiny notice; Section 270(10) regular assessment |
This distinction matters because AY 2026–27 and Tax Year 2026–27 are not the same period. The Income Tax Department confirms that scrutiny of AY 2026–27 and earlier years remains under the 1961 Act even if the notice or assessment occurs after 1 April 2026. The new Act contains a comparable scrutiny-notice provision in Section 270(8). Sources: Income Tax Department transition FAQs Official ↗ and Income-tax Act, 2025, as amended Official ↗.
First 5 things to do after receiving a scrutiny notice
Your immediate response plan
-
Confirm authenticity
Use the Income Tax Department's Authenticate Notice/Order facility and check the DIN or the document's identifying details.
-
Identify the correct year
Note the PAN, assessment year or tax year, relevant section, notice issue/service details and response deadline.
-
Read every question
Separate information requests from statutory warnings; download all attachments and questionnaires.
-
Gather supporting records
Match each point to the relevant books, statements, invoices, contracts, certificates and return schedules.
-
Submit and retain proof
File a focused response through e-Proceedings, then download the submission acknowledgement or transaction reference.
How to check whether the notice is genuine
Open the official Income Tax e-filing portal Official ↗, find Authenticate Notice / Order issued by ITD, and verify using either the DIN or the prescribed PAN/document details. The portal explains the verification options and OTP process in its authentication user manual Official ↗.
Most department communications are required to carry a DIN, subject to recognised procedural exceptions. Do not assume an email attachment is authentic simply because it uses an Income Tax logo. If verification fails, investigate through the portal or an adviser rather than following links or payment requests inside a suspicious message.
Scrutiny notice time limits: department and taxpayer
A notice has two different clocks: when the department must serve it, and when you must respond.
| Event | General position for AY 2026–27 and earlier |
|---|---|
| Notice under Section 143(2) | Must be served within three months from the end of the financial year in which the return is furnished |
| Your response | By the date specified in the actual notice; there is no reliable universal “15 days” for every scrutiny case |
| Normal completion of scrutiny assessment | Generally 12 months from the end of the relevant assessment year, subject to statutory extensions or exclusions |
| Extension of response time | An online Seek Adjournment option may be available; request an extension promptly and provide a reason |
Date example: If a taxpayer files the return for AY 2026–27 on 20 July 2026, the financial year of filing ends on 31 March 2027. The ordinary Section 143(2) service deadline is therefore 30 June 2027. This is a hypothetical illustration of the statutory rule, not proof that a specific notice is valid or invalid.
An assessment involving a transfer-pricing reference, court stay or special statutory circumstances can have a different completion calculation. The validity of service can also be disputed on case-specific facts; it should not be decided from a date typed in an article alone.
Official reference: Income Tax Department assessment time-limit guide Official ↗.
Limited scrutiny vs complete scrutiny: what changes?
The department has historically distinguished between limited and complete scrutiny in its selection and administrative instructions. The selection type and scope should be checked against the actual notice, related communications and applicable CBDT instructions; not every notice conveniently spells out every question in its first paragraph.
| Point | Limited scrutiny | Complete scrutiny |
|---|---|---|
Typical scope | Identified risk parameters or issues | Wider examination of the return |
Example | Particular cash deposits or capital gains | Multiple sources of income, claims and records |
Your preparation | Start with records relevant to the identified issues | Prepare a wider reconciliation of the return and books |
Can its scope change? | Only subject to applicable procedure and approvals | The applicable inquiry may already be broader |
If a question appears unrelated to the stated scope of a limited scrutiny case, do not simply refuse it. Ask your tax professional to examine the selection instructions, subsequent communications and applicable authorisation, and then respond appropriately.
143(1) vs 143(2) vs 142(1) vs 148
| Section (1961 Act) | What it generally means | Your likely action |
|---|---|---|
143(1) | Return processing/intimation and permissible adjustments | Check the computation; respond or rectify where applicable |
143(2) | Notice initiating scrutiny of a filed return | Review the proceeding and prepare evidence |
142(1) | Inquiry calling for information, documents or a return, as applicable | Answer each question and upload records |
148 / 148A | Reassessment-related proceedings under their separate conditions | Check the statutory grounds and procedural deadlines |
The fact that a return was processed under Section 143(1), or that a refund was issued, does not automatically prevent a valid scrutiny proceeding. See TaxQue's guide to notices under Section 142 and its general income-tax notice guide.
How to reply to a scrutiny notice online: step by step
Step 1: Sign in and locate the proceeding
Go to incometax.gov.in Official ↗, sign in with the taxpayer account and open Dashboard → Pending Actions → e-Proceedings → For Your Action. The exact on-screen wording can change; follow the portal's current e-Proceedings menu and select the notice for the correct year and PAN.
Step 2: Download all notices and questionnaires
Read the main notice PDF, any annexures and later communications. Note the proceeding reference, the response-due date, the document list and whether the department has sought an issue-wise explanation, a reconciliation statement or additional evidence.
Step 3: Prepare a point-by-point explanation
Number your reply in the same order as the department's questions. For each issue: state the facts → explain the reconciliation → identify the supporting document → refer to the applicable tax treatment. Do not use generic statements such as “all transactions are genuine” without evidence.
Step 4: Upload evidence with meaningful filenames
Examples include 01_Bank_Reconciliation.pdf, 02_Sale_Deed.pdf and 03_Capital_Gains_Working.pdf. Match filenames to a short document index so the assessing unit can follow the evidence. Check the current portal restrictions on file formats and attachment sizes rather than assuming a fixed upload limit.
Step 5: Submit and save the acknowledgement
Use Submit Response, review the declaration, confirm the attachments and submit. Retain the submission transaction ID or acknowledgement and a copy of everything uploaded. The official e-Proceedings FAQ states that a submitted response cannot be edited, making the final review important.
Step 6: Check for follow-up queries
Return to the portal regularly for questionnaires, hearing communications, show-cause notices, video-conferencing opportunities and the final order. Do not rely only on email or SMS notifications.
Source: Official e-Proceedings FAQ Official ↗ and e-Proceedings user manual Official ↗.
Document checklist for a Section 143(2) scrutiny response
Which documents you need depends on the actual questions. The following is a practical starting point, not a requirement to upload every document in every case.
| Issue questioned | Records commonly used to explain it |
|---|---|
| Salary, interest or TDS mismatch | Form 16/16A, Form 26AS, AIS, bank interest certificates, salary computation |
| Cash deposits or bank credits | Complete bank statement, cash book, source-of-funds reconciliation, sale/loan/gift evidence |
| Business turnover or expenses | Books, invoices, GST returns, ledger, bank reconciliation, expense vouchers |
| Capital gains | Contract notes, purchase/sale records, demat or mutual-fund statements, computation and supporting cost proofs |
| Loans or unsecured credits | Loan agreement, lender identity and confirmations, bank transfer trail, repayment evidence |
| Deductions or exemptions | Investment receipts, eligible payment proofs, certificates and relevant schedules |
| Property transactions | Sale deed, purchase deed, stamp-duty records, payment trail and capital-gain working |
| Foreign income/assets | Foreign statements, income documents, tax-credit evidence and relevant ITR disclosures |
Prepare one reconciliation sheet per questioned item. A bank-credit query is easier to answer when each questioned entry is linked to its date, amount, nature, source, book entry and supporting attachment.
Example: bank deposits questioned during scrutiny
Imagine a taxpayer declared ₹8 lakh as professional receipts, while the department identifies ₹13 lakh of bank credits. That does not automatically prove ₹5 lakh of undisclosed taxable income.
After reconciling the bank account, the taxpayer identifies the following hypothetical amounts:
| Source of deposits | Amount |
|---|---|
| Professional receipts already included in ITR | ₹8,00,000 |
| Transfer from own second bank account | ₹2,00,000 |
| Documented repayment of an earlier personal loan | ₹3,00,000 |
| Total credits | ₹13,00,000 |
The reply should show (1) where the ₹8 lakh was recorded and taxed, (2) both sides of the ₹2 lakh inter-account transfer, and (3) the original loan and repayment trail for the remaining ₹3 lakh. Whether each amount is taxable depends on the underlying facts and law; calling a receipt a “loan” is not sufficient by itself.
This approach is more persuasive than submitting a bank statement alone and expecting the department to infer the explanation. See TaxQue's guide to cash-deposit notices.
How to structure a scrutiny reply letter
A reply does not need complicated language. It needs accurate facts, complete evidence and a clear connection to the questions asked. A practical structure is:
- Reference details: PAN, assessment year, DIN/notice reference and date.
- Issue-wise response: Restate Question 1 and answer it, then Question 2, and so on.
- Reconciliation: Explain the figures with a concise table if useful.
- Supporting documents: Give numbered attachments and page references.
- Closing request: Ask that the submitted explanation and records be considered, and indicate that further information can be furnished if requested.
Do not submit fabricated confirmations, backdated agreements or reconstructed documents represented as contemporaneous originals. If a record is unavailable, explain that fact and provide credible alternatives where possible.
What happens during faceless assessment?
Many scrutiny cases are handled electronically through the faceless assessment framework. The National Faceless Assessment Centre and relevant assessment units coordinate notices, requests for material and decisions under the applicable law. Do not assume that every single assessment follows exactly the same faceless route: case allocation and exceptions depend on current rules and the proceeding.
If further questions arise, the portal may send a questionnaire or a show-cause notice explaining proposed additions. Read the proposal carefully and respond with documents and legal reasoning before the specified deadline. A hearing by video conference may be available under the governing procedure.
For older years, see Section 144B, Income-tax Act, 1961 Official ↗. For the new-law framework, see the Income-tax Act, 2025 Official ↗.
Can you request more time to respond?
Yes, where the applicable online facility permits it, use Seek Adjournment and explain why more time is needed—for example, bank records are being collected or a reconciliation requires third-party confirmations. Submit the request before the response deadline wherever possible, and check whether an extension was actually granted.
An adjournment request is not automatically an extension. Until the department accepts it or communicates a new date, treat the original deadline seriously.
The department provides an e-Proceedings user manual Official ↗ describing the online reply and adjournment workflow.
What if you ignore the scrutiny notice?
Non-response can allow the department to proceed on available records and, where statutory conditions are satisfied, make a best-judgment assessment under Section 144 for cases governed by the 1961 Act. Additional tax, interest or separate non-compliance consequences may arise depending on the facts.
Do not assume that every scrutiny notice results in a penalty. Likewise, do not assume that every discrepancy will be accepted without proof. Penalty provisions, possible relief and appellate options are fact-specific and may be affected by amendments relevant to the assessment date.
If you have already missed the due date, check immediately whether the proceeding remains open, whether a response can still be submitted, and whether a final order has already been passed. A professional review becomes particularly important when an assessment order or demand has been issued.
What happens after scrutiny assessment?
Possible outcomes include:
- No change: the assessment accepts the reported income after verification.
- Adjustment/addition: the order changes assessed income, disallows a claim or computes additional liability.
- Refund/demand consequences: an earlier refund might require adjustment, or a fresh demand might arise.
- Further action: depending on facts, penalty proceedings or appellate remedies may be relevant.
If you disagree with the order, obtain advice about an appeal to the competent appellate authority and any demand-stay application. For older assessment years, the usual first-appeal deadline is generally 30 days from the relevant service of demand or order, subject to the specific statutory rule and possible condonation. Do not wait for a reminder from the department.
Final checklist before you click Submit
- ○ Confirm the notice in the official e-filing account and verify authenticity.
- ○ Match PAN, year, notice section, issue details and deadline.
- ○ Download every questionnaire and attachment.
- ○ Reconcile figures to ITR, AIS, Form 26AS, bank records and books.
- ○ Answer each requested point directly and truthfully.
- ○ Prepare a numbered document index and readable attachments.
- ○ Review the draft and supporting files before final submission.
- ○ Save the acknowledgement and watch for further communications.
When to ask for professional assistance
Consider specialist assistance when the notice concerns substantial cash deposits, capital gains, unexplained credits, foreign assets, a company/LLP tax audit, a possible jurisdictional defect or a proposed addition with significant tax exposure.
TaxQue can help you organise the documentation and understand the income-tax notice resolution service. For a complicated assessment or representation before the authorities, confirm the scope of services and the qualifications of the professional who will handle your case.
Explore income-tax notice assistance
Official sources and further reading
- Income Tax Department — Income-tax return transition FAQs Official ↗: confirms older-year proceedings remain under the 1961 Act.
- Income Tax Department — Section 143 of the 1961 Act Official ↗: scrutiny-notice and assessment provisions.
- Income Tax Department — Income-tax Act, 2025, as amended Official ↗: Sections 270(8)–(10) for scrutiny under the new law.
- Income Tax Department — Notice and assessment time limits Official ↗: statutory deadlines for earlier years.
- Income Tax Department — Authenticate a notice Official ↗: genuine-notice checks.
- Income Tax Department — e-Proceedings FAQs Official ↗: online response, tracking and editing limitations.
- Income Tax Department — Section 144B Official ↗: faceless assessment under the old Act.
Editorial review: 17 October 2026. This guide is general information, not a finding on the validity of any individual notice. Always follow the actual notice, applicable law and current official portal instructions.