Customer Support
TaxQue
Contact Us
Income Tax Services

ITR-3 Filing

Estimated timeline *5–7 Working Days

Estimated delivery

Timeline conditions

The estimate starts once complete documents, required information and payment are received. Working days exclude weekends and public holidays. Requests for clarification or corrections may extend the timeline. Government processing and approval times are outside TaxQue’s control; this is an estimate, not a guaranteed completion date.

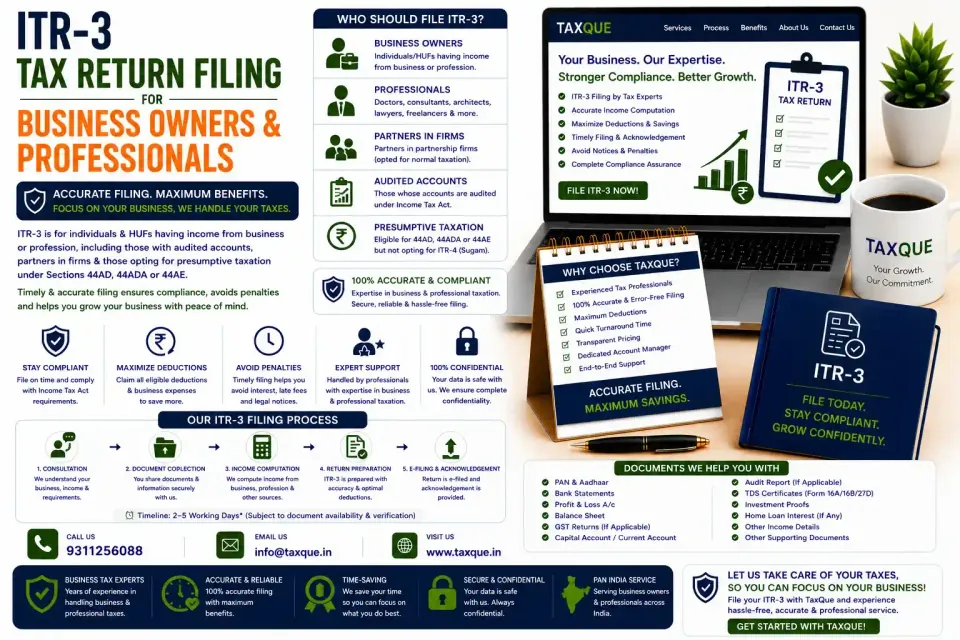
For Sole Proprietors, Doctors & Consultants: Required for individuals and HUFs carrying on a business, profession, or partner in a partnership firm.

Full Balance Sheet & P&L Reporting: Detailed statutory reporting of gross turnover, depreciation schedules, business expenses, and closing stock.

Tax Audit & Section 44AB Guidance: Corporate tax team reviews your books and reconciles accounts in strict compliance with ICAI standards.

100%Online Process
24hrExpert Callback
₹0Consultation Fee
Expert Available Now

Get Free Expert Consultation

No commitment · Callback within 24 hrs

+91
Loading security check…

By submitting, you agree to be contacted by TaxQue's expert team.
Your data is safe and never shared.

Pricing

Right Plan For ITR-3 Filing

Transparent pricing. No hidden charges.

Basic

₹1,999/Annually
₹3,00033% off

Essential ITR-3 return filing for proprietary business owners and consulting professional income.

WHAT'S INCLUDED

5 benefits
  • ✓Complete Form 16, AIS, TIS & 26AS Tax Credit Verification
  • ✓Accurate Income Computation & Deductions Review (80C, 80D, HRA)
  • ✓Optimal Tax Regime Selection (New vs Old Regime Comparison)
  • ✓Official Income Tax Department e-Filing & ITR-V Acknowledgment
  • ✓Automated Refund Tracking & CPC Intimation Verification
⭐Most Popular

Standard

₹4,999/Annually
₹7,00029% off

Comprehensive ITR-3 filing with dedicated CA, balance sheet review, and expense optimization.

WHAT'S INCLUDED

9 benefits
  • ✓Complete Form 16, AIS, TIS & 26AS Tax Credit Verification
  • ✓Accurate Income Computation & Deductions Review (80C, 80D, HRA)
  • ✓Optimal Tax Regime Selection (New vs Old Regime Comparison)
  • ✓Official Income Tax Department e-Filing & ITR-V Acknowledgment
  • ✓Automated Refund Tracking & CPC Intimation Verification
  • ✓Assigned Senior Chartered Accountant (CA) Tax Specialist
  • ✓Capital Gains (Stocks, Crypto, Property) & Loss Carry-Forward Review
  • ✓Business Balance Sheet & Profit & Loss Statement Scrutiny
  • ✓Section 143(1) Intimation Verification & Defect Rectification Support

Premium

₹7,999/Annually
₹12,00033% off

Complete business tax suite with Section 44AB audit review, planning, and defense.

WHAT'S INCLUDED

13 benefits
  • ✓Complete Form 16, AIS, TIS & 26AS Tax Credit Verification
  • ✓Accurate Income Computation & Deductions Review (80C, 80D, HRA)
  • ✓Optimal Tax Regime Selection (New vs Old Regime Comparison)
  • ✓Official Income Tax Department e-Filing & ITR-V Acknowledgment
  • ✓Automated Refund Tracking & CPC Intimation Verification
  • ✓Assigned Senior Chartered Accountant (CA) Tax Specialist
  • ✓Capital Gains (Stocks, Crypto, Property) & Loss Carry-Forward Review
  • ✓Business Balance Sheet & Profit & Loss Statement Scrutiny
  • ✓Section 143(1) Intimation Verification & Defect Rectification Support
  • ✓Comprehensive Multi-Year Tax Planning & Financial Structuring
  • ✓Defense & Legal Drafting for Scrutiny Notices (Section 148 / 142(1))
  • ✓Advance Tax Estimation & Quarterly Payment Scheduling
  • ✓Direct One-on-One Tax Consultation with Senior Partner

ITR-3 Tax Return Filing for Business Owners, Professionals & F&O Traders

ITR-3 is the comprehensive direct tax return form under the Income Tax Act, 1961 for individuals and Hindu Undivided Families (HUFs) who carry on a proprietary business, exercise a profession (doctors, lawyers, architects, consultants), or trade in Futures & Options (F&O) and intraday equities. It requires detailed reporting of balance sheet assets, profit and loss statements, and depreciation schedules.

TaxQue provides full-stack corporate and direct tax advisory for business owners. Our Chartered Accountants structure your business expenses, calculate allowable depreciation under Section 32, reconcile turnover with GST returns, determine tax audit applicability under Section 44AB, and prepare compliant financial statements for submission.

What is ITR-3 Filing?

ITR-3 is the mandatory direct tax return form for individual proprietors, consultants, and active equity/derivative traders declaring business or professional income under Chapter IV-D of the Income Tax Act.

ITR-3 Filing — TaxQue Statutory Services

Sole Proprietors & Commercial Merchants: Mandatory for all individual business owners operating wholesale, retail, manufacturing, or service enterprises not opting for presumptive taxation.

Consulting Professionals & Freelancers: Applicable to doctors, advocates, engineers, IT consultants, and creative freelancers who maintain regular books of accounts.

Futures & Options (F&O) & Intraday Stock Traders: Mandatory under Section 43(5) because F&O is treated as non-speculative business income and intraday trading is treated as speculative business income.

Section 44AB Tax Audit Mandate

If business turnover exceeds ₹10 Crore (where 95% transactions are digital) or ₹1 Crore (in cash mode), a Tax Audit Report in Form 3CA/3CB-3CD by a practicing Chartered Accountant is mandatory before filing ITR-3.

Process

How to Get Started

1

Ledger Ingestion & GST-Turnover Reconciliation

Books Upload -> GSTR-1 vs Financial Turnover Matching -> Expense Scrutiny

  1. 1Upload profit & loss accounts, balance sheets, bank statements, and trading P&L reports on TaxQue.
  2. 2CA reconciles reported business turnover against 12 months of GSTR-1 and GSTR-3B filings.
2

Business Expense Optimization & Depreciation Modeling

Disallowance Check (40A(3)/43B) -> Block of Assets Depreciation -> Net Profit Review

  1. 1Scrutinize business expenses for Section 40A(3) cash limits, 40(a)(ia) TDS disallowances, and 43B statutory dues.
  2. 2Calculate block-wise statutory depreciation on computers, plant, machinery, vehicles, and commercial buildings.
3

Portal e-Filing & Audit Integration

Schedule BP / Balance Sheet Preparation -> DSC Verification -> ITR-V Delivery

  1. 1Compile Schedule BP (Business/Profession), Schedule BS (Balance Sheet), Schedule PL, and Form 3CD audit data.
  2. 2File on the CBDT e-filing portal using Class 3 Digital Signature Certificate or Aadhaar EVC.
Documentation

Documents Required for ITR-3 Filing

Financial ledgers, bank books, and statutory tax registers required for business assessment.

Swipe horizontally to view table👉
Data CategorySpecific Documents RequiredVerification Notes
Financial StatementsTrial Balance, Balance Sheet, Profit & Loss Account, Depreciation ScheduleDrafted as per ICAI accounting standards
Bank Account StatementsAll current and savings bank accounts active during the financial yearReconciled with books and AIS cash data
GST & TDS RecordsAnnual GSTR-9 / GSTR-1 summary, Form 26AS, Form 16A TDS certificatesMust match reported business turnover
Trading & Investment P&LConsolidated P&L statement from Zerodha/Groww for F&O, intraday, and deliveryRequired for speculative vs non-speculative division
Tax Audit Report (If Applicable)Form 3CB-3CD signed by practicing Chartered AccountantMandatory if turnover exceeds statutory limits
Due Date

Statutory Deadlines & Penalty Matrix for ITR-3

Timelines under Section 139 and Section 44AB of the Income Tax Act.

Swipe horizontally to view table👉
Taxpayer CategoryStatutory Due DatePenalty / Consequence of Default
Non-Audit Business / Professional31st July of Assessment Year₹5,000 late fee under Section 234F + Loss carry-forward disallowance
Tax Audit Cases (Section 44AB)31st October of Assessment Year₹1.5 Lakhs or 0.5% of turnover penalty under Section 271B for audit delay
Tax Audit Report Filing (Form 3CD)30th September of Assessment YearMandatory CA sign-off 1 month prior to ITR due date
Belated Return Deadline31st December of Assessment Year1% per month interest under Section 234A on unpaid tax liability
Threshold

Tax Audit & Presumptive Turnover Thresholds

Statutory turnover limits governing business taxation.

Swipe horizontally to view table👉
Statutory RuleTurnover ThresholdGoverning Section
Tax Audit (Digital Transactions > 95%)Turnover exceeding ₹10 Crore in a FYSection 44AB(a) Income Tax Act
Tax Audit (Cash Mode > 5%)Turnover exceeding ₹1 Crore in a FYSection 44AB(a) Income Tax Act
Tax Audit for ProfessionalsGross Receipts exceeding ₹50 Lakhs / ₹75 LakhsSection 44AB(b) Income Tax Act
Mandatory Maintenance of AccountsIncome > ₹2.5L or Turnover > ₹25L in any 3 prior yearsSection 44AA Income Tax Act
Benefits

Why Choose ITR-3 Filing

Why ambitious business founders and active traders choose TaxQue.

📊

Complete Balance Sheet & P&L Structuring

Our Chartered Accountants compile professional financial balance sheets, ensuring clean banking profiles for loan sanction.

🧮

F&O Derivatives & Intraday Tax Optimization

We correctly classify non-speculative derivative turnover and claim allowable trading expenses (STT, brokerage, internet, advisory).

🏆

Seamless Tax Audit (44AB) Integration

In-house team of practicing CAs to execute tax audits and file Form 3CD without requiring external consultants.

Eligibility

Eligibility Criteria for ITR-3

Taxpayers legally mandated to file Form ITR-3.

1Eligible Entities

  • Individuals and HUFs carrying on business or profession as sole proprietors.
  • Partners in partnership firms or designated partners in LLPs (reporting partner salary/interest).
  • Stock traders conducting intraday equity, commodities, and derivatives (F&O) transactions.

TaxQue ITR-3 Service vs Generic Software Portals

Why complex business returns require dedicated CA handling.

Swipe horizontally to view table👉
ParameterTaxQue Dedicated Business CA DeskAutomated Online DIY ToolsLocal Inexperienced Tax Preparer
F&O Turnover CalculationStrict compliance with amended ICAI guidance (Absolute Profit/Loss)Often calculates aggregate turnover causing false audit triggersUnfamiliar with derivative turnover rules
Depreciation SchedulesBlock of assets accounting strictly under Section 32Basic single-rate formula (misses 15%/40% asset rules)Manual calculation prone to errors
Section 43B / 40A(3) AuditProactive disallowance check before filingZero statutory disallowance checksMisses cash payment violations
Audit Defense GuaranteeComplete legal representation for Section 143(3) scrutinyZero audit supportCharges high separate fees
Features

Key Features of TaxQue ITR-3 Services

Comprehensive, audit-ready direct tax compliance for businesses.

📑

Complete Financials Preparation

Preparation of formal Balance Sheets, Profit & Loss accounts, and Depreciation registers.

🛡️

Business Expense Maximizer

Legitimately claim all allowable business expenses to minimize net taxable profit.

✅

Bank Loan Readiness

Ensure financial statements meet bank credit appraisal standards for CC/OD limits.

FAQ

Frequently Asked Questions

Quick answers about ITR-3 Filing

ITR-3 is mandatory for individuals and HUFs having income from Profits and Gains of Business or Profession (PGBP) who maintain regular Books of Accounts, trade in Futures and Options (F&O), do intraday stock trading, are partners in a partnership firm, or exceed presumptive turnover limits. Our team handles complete balance sheet and P&L finalization.

Under Section 43(5) of the Income Tax Act, F&O trading is categorized as Non-Speculative Business Income and Intraday equity trading is Speculative Business Income. All brokerage, internet, advisory, and depreciation expenses can be deducted against trading profits in ITR-3, and trading losses can be set off or carried forward.

Tax audit by a practicing Chartered Accountant is mandatory if business turnover exceeds ₹1 Crore (or ₹10 Crores if cash transactions are ≤ 5% of total receipts/payments). For professionals, the audit threshold is gross receipts exceeding ₹50 Lakhs (or ₹75 Lakhs under Section 44ADA). TaxQue provides complete in-house CA tax audit (Form 3CA/3CB-3CD) services.

For non-audit businesses and traders, the due date is 31st July. For businesses subject to mandatory Tax Audit under Section 44AB (or partners in audited firms), the tax audit report must be uploaded by 30th September and the ITR-3 filed by 31st October.

Your financial statements and return are prepared by a dedicated business tax accountant and audited by a practicing Chartered Accountant. We prepare your Balance Sheet, Profit & Loss statement, and depreciation schedules in full compliance with Income Computation and Disclosure Standards (ICDS).

CLIENT REVIEWS

What Our Clients Say

Real experiences from 500+ businesses and individuals who trust TaxQue across India.

RA

Ramesh Agarwal

1y ago

Google
5.0

Excellent GST Service

TaxQue handled our entire GST compliance smoothly. The team was responsive and very professional. Absolutely recommend to any business owner!

GST Filing
ITR-3 Filing
From₹1,999
Newsletter

Stay Updated with Tax Insights

Get expert tax tips, GST updates & compliance guides delivered to your inbox.

🔒 No spam. Unsubscribe anytime.